This guide explains how to use Runpayroll.adp.com for payroll processing, access control, and smoother operations. It objectively reviews what payroll portals typically manage, why login and permissions matter, and how organizations reduce errors through structured workflows. You’ll also find a comparison table of common setup approaches, requirements, and practical conditions to verify before go-live.
If you’re trying to streamline payroll operations, Runpayroll.adp.com is best approached as a controlled workflow environment: confirm user permissions, verify data inputs, and follow a repeatable approval cadence. From an industry perspective, the biggest wins usually come not from “accessing the portal,” but from establishing consistent controls around who can do what, when—especially during pay-cycle deadlines. Payroll failures are rarely caused by a single action; more often, they emerge from a chain of small process weaknesses (unclear ownership, missing validation steps, last-minute edits, or approval bottlenecks that no longer reflect real review).
Responsible use also means treating the portal as part of your broader governance system rather than a standalone tool. That broader system includes HR data governance, timekeeping controls (if applicable), finance reconciliation practices, security policies, audit response procedures, and training. When those elements align, you reduce operational risk while improving speed and confidence. When they don’t align, even a technically functioning portal can produce outcomes that are late, incomplete, or difficult to explain—creating stress for payroll teams and downstream problems for employees.
In the sections that follow, you’ll find a framework you can adapt regardless of your exact configuration. Although portals like Runpayroll.adp.com may present different screens and labels depending on your organization and the modules enabled, the core operational responsibilities remain similar: manage inputs, validate calculations, control changes, run processing under a defined calendar, and reconcile results using evidence.
Payroll systems, including services reached through domains like Runpayroll.adp.com, typically centralize tasks such as employee pay calculations, pay-cycle scheduling, payroll edits, and distribution of payroll-related outputs (for example, earnings and deductions views, payroll registers, and submission artifacts). While specific capabilities depend on your organization’s configuration, most portals exist to reduce manual handling, standardize processing steps, and provide an auditable record of changes.
In practice, organizations rely on these portals because payroll is a high-complexity process: it touches HR data, tax and compliance rules, time or attendance inputs, benefits elections, and company-specific policies. Even small inconsistencies—like outdated employee details, incorrect pay group assignment, or mismatched deduction setups—can cause downstream corrections. Those corrections often appear as retroactive adjustments, re-runs, or manual offsets in subsequent cycles. A well-run portal workflow helps prevent that “drift” by enforcing repeatable checkpoints.
It also matters that payroll is both time-sensitive and sensitive. “Time-sensitive” means you cannot fix many issues after cutoffs without triggering wage payment delays or employee dissatisfaction. “Sensitive” means payroll data is confidential: it includes personal information, earnings details, deductions, and sometimes banking or benefit-related identifiers. Portals provide access control, audit logging, and structured review tools—but only if your organization configures and uses them correctly.
From a control perspective, portals commonly regulate at least four categories of activity:
The most reliable organizations treat those categories as “control points.” Instead of asking only “can we run payroll from the portal?”, they ask “do we have evidence that the portal ran the correct configuration using approved data, with appropriate approvals and traceability?” That shift in mindset turns the portal into an auditable operational system.
Before running payroll through any environment connected to Runpayroll.adp.com, treat setup as a sequence of validations rather than a one-time action. A practical approach is to confirm, in order:
Industry top practice is to build these validations into a repeatable checklist so the team doesn’t rely on memory during high-pressure periods. This is especially important as staffing changes occur—new hires in HRIS, finance analysts, payroll operators, or approvers. A repeatable checklist reduces risk of omission.
From a governance viewpoint, these checks reduce operational risk and avoid “last-minute fixes” that are common causes of payroll rework. Last-minute fixes can be dangerous because they often bypass review, compress testing, or shift accountability. Even if the fix is correct, the process may still violate your internal controls—creating auditability problems and increasing the chance that the same issue repeats in future cycles.
It can also help to distinguish between “configuration setup” and “operational setup.” Configuration setup includes pay groups, earning/deduction mappings, tax configuration, and integration rules. Operational setup includes verifying that the right employees are included in the run, that the correct pay cycle is active, and that any special exceptions have been handled. Both matter, but teams sometimes focus only on configuration and forget operational readiness, leading to surprises on run day.
While the exact screens and labels vary, an expert payroll operations workflow typically looks like this:
This structure is common across enterprise payroll environments because it creates predictable checkpoints where errors are easier to detect and less expensive to fix. The workflow also supports continuity: when something goes wrong, you can pinpoint where in the process the failure occurred (inputs, validation, approval, or execution).
To make the workflow resilient, consider adding explicit evidence requirements at each step. For example:
Even if your organization doesn’t formalize evidence with documents, the practice of “what proof do we have?” changes behavior and reduces compliance risk.
Many payroll issues don’t originate from calculation logic—they originate from process gaps. For example, if too many users can modify payroll inputs without oversight, errors can be introduced without detection. Conversely, if approvers lack visibility into changes, approvals may become rubber-stamp activities rather than informed review.
For portals like Runpayroll.adp.com, consider adopting the following control philosophy:
Separation of duties is particularly important during cutoffs. Many errors occur when teams are rushing and someone with broad access applies a quick change. If that same person is also the only approver, the control is weak. A robust approval model ensures that a separate person checks that the change is legitimate, correctly mapped, and consistent with policy.
Another common issue is role creep over time: as responsibilities shift, permissions remain unchanged. For instance, a user might initially be assigned to “run payroll preview” but later starts making corrections directly, without formally changing their role. Least privilege policies should include periodic access reviews and a clear mechanism for updating roles.
In practical terms, access control involves three activities:
This approach aligns with widely recognized internal control practices. For general guidance on controls, organizations often reference frameworks discussed by professional bodies such as the International Organization for Standardization (ISO) and COBIT (IT governance) principles, as well as standard internal control guidance from audit organizations.
It’s also helpful to treat “approval” as an operational responsibility, not a checkbox. Approvers should understand what the portal represents, what data is being used for the run, and what exceptions matter. When approvers don’t understand the portal outputs, approvals can become performative rather than protective.
Payroll accuracy depends on correct inputs. Common friction points include:
To manage these, payroll teams typically maintain a reconciliation routine: compare pre-run expected outcomes with post-run confirmations, then record any deviations and their resolution rationale. The goal is not only to correct outcomes, but to improve process consistency across pay cycles.
Reconciliation can be thought of as a “controlled reasoning process.” Instead of relying on the portal output alone, you cross-check key totals and known rules. While the exact methods vary, examples of reconciliation evidence include:
Reconciliation becomes even more important when you have integrated timekeeping systems. If time inputs arrive late or in a different format, the portal might still process them correctly—but incorrect or incomplete time can create payment errors. Reconciliation helps you detect that problem even if the portal itself does not flag it as an exception.
Also consider the difference between “system correctness” and “business correctness.” A portal might compute taxes and deductions accurately based on whatever data it received, but if the input data was wrong (e.g., wrong pay group or wrong deduction code), the computation is still “correct” from the system’s viewpoint and wrong for your business and employees. Reconciliation is where you align system outputs with business expectations.
You mentioned “price information” and “supplier details,” but no specific numeric price was provided. In this guide, the professional way to handle that is to evaluate pricing structure and supplier responsibilities through verifiable channels such as your contract, vendor quotes, and official documentation.
In payroll procurement, pricing models often reflect factors like employee count, modules enabled, support tiers, integration scope, and implementation services. For supplier due diligence, focus on:
If you want, share the country/region and approximate workforce size you’re planning for—then you can build a checklist of what to ask your supplier and how to map costs to requirements. For accuracy and compliance, it’s better to avoid quoting numbers that are not sourced from your contract or official vendor documentation. Instead, tie cost items to measurable outcomes (hours of implementation, number of integrations, report types included, support hours, and any additional compliance features required).
Beyond price, organizations often underestimate the cost of operational readiness. For instance, implementing a payroll portal successfully requires training and process design. If your supplier quote doesn’t reflect implementation support for role-based access design, exception taxonomy, and reconciliation methods, the operational cost often lands on your internal team. When evaluating “supplier details,” include:
In other words, don’t view supplier evaluation as a “price-only” decision. View it as a “who owns what” decision across the lifecycle: implementation, ongoing operations, support, security posture, and change management.
Payroll systems are high-value targets. While you’ll rely on the supplier’s security engineering, your organization still has responsibilities in configuration and operations. When working through portals like Runpayroll.adp.com, confirm:
For general, objective context on cybersecurity controls, many organizations reference guidance from recognized standards bodies and government cybersecurity agencies. For example, the NIST Cybersecurity Framework provides an organizing structure for security management, including identify, protect, detect, respond, and recover functions. Even if you don’t formally adopt the framework, it helps you ask the right questions about security ownership and operational maturity.
Security and reliability also include operational aspects that aren’t purely technical. Consider:
Reliability is crucial because payroll cutoffs compress timelines. A system outage during the final approval window can be catastrophic if your contingency plans are not prepared. Responsible portal use means planning for “what if the portal is unavailable?” and defining how decisions and documentation will be handled until access is restored.
Below is a supplement to help you decide how to structure payroll portal readiness. This is presented as a comparison of typical approaches (not as a vendor claim), and it assumes organizations are aligning around a controlled process connected to portals such as Runpayroll.adp.com.
| Setup approach | When it’s appropriate | Key benefits | Conditions/requirements to verify |
|---|---|---|---|
| Role-based access design first | When teams are large or payroll edits require oversight | Reduces unauthorized changes; strengthens approvals | Documented permission matrix; separation of duties; audit trail review process |
| Data readiness validation first | When many employee records or pay rules are new/complex | Fewer exceptions during run; faster pre-checks | Data governance ownership; reconciliation plan; sign-off for master data changes |
| Cutoff-driven workflow calendar | When deadlines are tight and dependencies exist (timekeeping/HR) | Predictable throughput; fewer last-minute corrections | Defined internal cutoffs; escalation path; contingency handling for missing inputs |
| Integrated testing with pilot cycles | When integrations or retroactive rules are likely | Finds edge cases before production processing | Test dataset approval; parallel validation; documented differences between test and production |
In reality, mature organizations blend these approaches. The key difference is prioritization and sequencing. For example, if your access control is weak, no amount of data validation will fully protect you from unauthorized changes. If your data readiness is weak, even the best role design can still lead to exceptions. If your cutoff workflow is unclear, you may pass approvals but miss the ability to detect issues before submission.
This practical guide is designed to be actionable for payroll operations teams, HRIS coordinators, and finance stakeholders. It assumes you will be accessing a portal environment such as Runpayroll.adp.com.
During the first payroll run, you should also pay attention to documentation habits. Many organizations improve quickly after the first cycle, but the improvement depends on whether you record what happened. For example, if an exception occurred because of missing benefits data, document: (1) the exception type, (2) why the data was missing, (3) how it was corrected, and (4) what step in the checklist should be improved next cycle.
Another important operational habit is to ensure that the preview/simulation results are treated as decision support, not as a “guarantee.” Previews can be limited, and exceptions may not capture everything. The reconciliation step and exception review step are your safety nets when previews are imperfect.
Even when the supplier provides the technology, organizations succeed by documenting the operating conditions. Consider documenting the following:
Documentation doesn’t need to be overly long, but it should be specific enough that a new team member can follow it. “Approve payroll” is not actionable; “approver reviews simulation results for exceptions and confirms payroll period and run identifier before submission” is actionable. Specificity reduces ambiguity during high-pressure periods.
It can also help to define “go/no-go” criteria for payroll submission. For instance, if critical exceptions remain unresolved by a certain point, the organization may delay processing or switch to a defined contingency approach. Having go/no-go criteria prevents the common failure pattern where teams attempt to run payroll regardless of unresolved issues.
From an industry operations standpoint, the maturity of payroll processing is less about having the latest interface and more about operational discipline. High-performing payroll teams tend to:
These behaviors create a “learning loop.” Instead of treating payroll issues as isolated incidents, teams interpret them as symptoms of upstream process weaknesses. For example, if payroll exceptions repeatedly relate to benefit eligibility dates, the team might adjust HR workflows or improve the cadence for benefit elections. If exceptions repeatedly involve pay rate changes, the organization might add validation controls to HRIS changes or tighten approval windows.
Another maturity marker is the presence of a reconciliation mindset. Teams that reconcile consistently can detect issues early—often before they appear as employee complaints. They also produce evidence that supports internal and external inquiries. Reconciliation is often seen as a finance activity, but payroll maturity requires close collaboration between payroll, HRIS, and finance.
In other words, the portal is the stage; the playbook is what determines the result. When the playbook is strong, the portal becomes a reliable mechanism for consistent execution.
To make this practical, consider how maturity shows up in day-to-day behavior:
Compare that to less mature behaviors: people making changes informally, skipping previews, allowing too many exceptions to remain unresolved, or treating reconciliation as optional. Even if those behaviors “work” occasionally, they create a high probability of failure when unusual events occur—such as mass pay adjustments, system integration disruptions, or major policy changes.
In general terms, Runpayroll.adp.com represents a payroll-run environment associated with ADP services. Organizations typically use such portals to process payroll, review results, manage payroll inputs through controlled workflows, and verify processing outputs. Exact functions depend on your configured modules and your access permissions.
In practical terms, the portal usually supports tasks like viewing run outputs, submitting payroll runs according to your internal workflow, reviewing exceptions, and tracking approval status. Some organizations also use the portal to view historical run results and to support adjustments or reporting related to prior periods.
Permissions control who can edit data, who can submit or approve a run, and who can view sensitive payroll information. Strong role-based access helps prevent accidental changes and supports auditability, which is especially important around payroll cutoffs.
Access permissions also matter for operational clarity. If too many users have broad permissions, you lose control. If too few users have necessary access, you can end up with delays during run week when issues need quick resolution. The goal is balance: enough access to keep workflow efficient, and enough restriction to preserve control and evidence.
Manual checks alone are rarely sufficient for mature payroll operations. Top practice combines portal-based validation steps (such as previews, exception review, and audit logs) with internal reconciliation and approval workflows.
Manual checks are still valuable: they include reasonableness checks, variance investigation, and ensuring that human understanding of policy is applied correctly. However, manual checks should be supported by structured evidence and consistent procedures. When manual checks are used without consistent process, they become dependent on individual judgment and can vary across cycles.
At minimum: employee master data accuracy, pay rules alignment, deduction and benefit setups, role permissions, exception handling procedures, and your internal cutoff/approval calendar. If you’re integrating timekeeping or other systems, test those dependencies as well.
For first-run readiness, emphasize high-risk areas. These often include:
Also verify that your team knows how to interpret the portal’s outputs and exceptions. If staff can’t confidently interpret what an exception means, the exception becomes a source of uncertainty rather than a risk-reduction tool.
Retroactive changes require disciplined handling: define when and how updates can be applied, ensure the changes are approved, and validate the impact through the portal’s preview/verification capabilities (where available). Maintain a documented approach to exceptions and re-validation after corrections.
Because retroactive changes can alter prior period calculations, they often require more than a simple re-run. Consider whether you need to generate retro pay, reverse previous deductions, or handle employee communications for corrected amounts. The portal may support those adjustments, but your process must confirm that the business rules align with expected treatment.
Use the official materials provided by your payroll supplier and your implementation team. For security and operational controls, also rely on recognized standards and frameworks (for example, NIST guidance) to structure internal governance.
In practice, documentation should include both “how to use the portal” and “how to operate the portal.” Operational guidance covers policies and controls: who approves, what evidence is required, and what steps must happen before submission. Implementation materials cover configuration details and system behaviors. Both categories matter.
Both matter, but in the right balance. Streamlining reduces friction, while approvals add control. The goal is to ensure approvals are meaningful: approvers should review the right information and have sufficient visibility into changes and exceptions.
One common failure pattern is excessive approvals that become routine and unhelpful. Another failure pattern is too few approvals that allow unauthorized or incorrect data changes. The right approach is to align approval points with risk level. High-risk changes require deeper approval. Low-risk routine actions may require lighter review but still need evidence and auditability.
No. Payroll workflows depend on workforce complexity, pay rules, compliance needs, and integration scope. The comparison approaches earlier in this guide—role-based access design, data readiness validation, cutoff-driven workflows, and pilot testing—can be combined, but the order and emphasis should match your risk profile.
For example, a small organization with limited integrations and straightforward pay rules might prioritize data readiness and cutoff workflow first. A larger organization with many users and complex deductions might prioritize access control and separation of duties first. A multinational company might emphasize integration testing and exception taxonomy due to jurisdiction complexity.
If your organization is currently evaluating how payroll operations should be organized, treat Runpayroll.adp.com as part of a broader system: HR data sources, timekeeping processes, finance reconciliation, and internal controls. A practical evaluation should include:
Also evaluate portal capabilities in your operating model. Ask: does the portal support preview and verification clearly enough for your reviewers? Does it provide audit logs at the level of detail you need? Does it let you separate duties effectively? If any of these capabilities are missing or insufficient, your internal process may need to compensate with alternate evidence sources.
Another consideration is how changes to the payroll system itself occur. For example, if the supplier updates configuration or if new modules are enabled, what is your change management plan? Payroll is sensitive to configuration changes, so a change that seems harmless in IT terms can affect employee pay outcomes. Responsible organizations handle portal change management with:
These steps are essential because “we didn’t change anything” is rarely true for payroll operations. The environment evolves: HR practices evolve, laws evolve, benefit rules evolve, and technology evolves. The governance model must evolve too.
Finally, evaluate how you handle incidents. An incident isn’t only a system outage. It can be a late time import, a misconfigured deduction, a missed approval, or a reconciliation variance that cannot be explained. You need an incident response approach that defines:
This incident response discipline reduces repeated mistakes and improves confidence with each pay cycle.
Accessing Runpayroll.adp.com is only the starting point. The operational value comes from disciplined workflows: role-based permissions, validated inputs, structured exceptions, and consistent reconciliation. When organizations build a reliable “runbook” around the portal, payroll becomes less reactive and more predictable—an outcome that benefits employees, finance teams, and leadership alike.
Responsible portal use ultimately means your organization can answer four questions with evidence each cycle:
When you can consistently answer those questions, you don’t just reduce errors—you build trust. Employees trust they are paid correctly and on time. Finance trusts that payroll outputs are auditable and reconciled. Leadership trusts payroll operations because they are governed, not improvised. And payroll teams gain a repeatable way of working that makes high-pressure periods more manageable.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
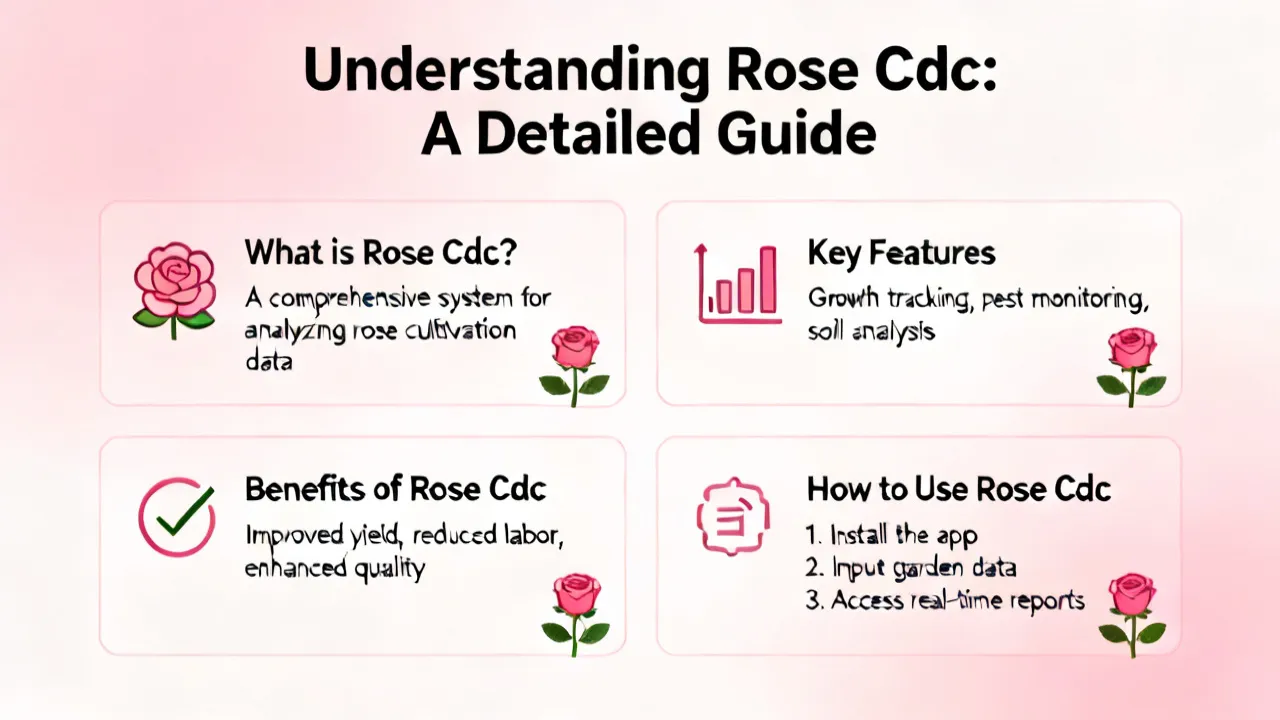
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.