This guide explains how employees typically evaluate Paychex 401(k) and Fidelity-related plan features, from enrollment and account setup to investment choices and administrative workflows. Background context clarifies how recordkeeping, payroll integration, and plan rules interact, with an expert, objective lens on due diligence and risk controls for retirement savers.
If you’re working with Paychex 401k Fidelity, your very important starting point is understanding the “plumbing” between payroll administration and retirement plan recordkeeping. In practice, Paychex often supports employer-side payroll and plan administration, while Fidelity commonly functions as a recordkeeper or investment platform within employer 401(k) ecosystems. The right approach is to compare your plan’s available investment options, fees, operational rules, and service experience—then align those details to your time horizon and contribution strategy.
From an industry perspective, the very valuable due diligence steps are: (1) confirm exactly who is your recordkeeper and where your investments are held, (2) review the plan’s fee disclosures and investment expense ratios, (3) verify contribution mechanics through your payroll schedule, and (4) ensure your beneficiary, rollover, and distribution rules match your personal circumstances. This reduces the risk of surprises later, such as misunderstanding when contributions are invested or how distributions are processed.
It also helps to adopt a participant mindset: you are not just “choosing a website” or “choosing a brand.” You are participating in a rules-based system governed by your plan documents. In most employer plans, those documents spell out timelines, cut-off rules, eligibility requirements, and the steps required to execute transactions. Paychex may touch the payroll file, HR may guide you through enrollment, and Fidelity may hold your account and execute investment trades—but the final authority is the plan’s written terms.
When that division of responsibilities is unclear, employees often experience anxiety or confusion: “Why did my contribution election not apply yet?” “Why hasn’t my balance updated?” “Is my employer match missing?” “How long does a rollover take?” Many of these issues are not caused by any single company; they are caused by the normal timing and operational constraints built into the payroll-to-recordkeeping workflow. Your best defense is to verify the plan’s operational rules and keep your own records of elections and transactions.
Many employer-sponsored retirement programs are built from multiple service components. Typically, employers choose administrative support (often payroll- or HR-adjacent). Separately, a recordkeeper maintains participant accounts, handles transactions such as contributions and exchanges, and supplies statements and online account access. In this landscape, Paychex 401k Fidelity usually signals that an employer’s 401(k) arrangement may involve both parties—often with Paychex supporting administration and Fidelity supporting the recordkeeping and investment interface.
What matters for participants is not the brand name itself, but the operational reality:
What’s often overlooked is that the workflow may have several stages. For example, an employee submits an enrollment or salary deferral change through a payroll portal; HR exports payroll data through the administrative system; the payroll file transmits contribution amounts for the pay period; the recordkeeping platform receives the contribution file; then the recordkeeper posts the contribution to your account; and finally your election is used to invest the contribution according to plan rules. Each stage can have its own cut-off time, processing date, and posting timeline.
In day-to-day terms, that means you should expect that changes might not be reflected instantly. Many employees incorrectly assume “I changed my 401(k) election on Monday, so it should apply to the Monday payroll.” The plan’s cut-off time is what controls. Cut-off time is typically defined in plan documentation or in enrollment materials, and it may differ for different types of actions. A contribution election might have one cut-off, while an investment exchange might have another. Beneficiary updates might be effective immediately or effective as of the date Fidelity receives and validates the form. That’s why you should look for the effective date language in your plan communications.
Another practical point is that Paychex 401k Fidelity may mean different things depending on your employer’s setup. Some employers might use Paychex for payroll data and administration only, while Fidelity does the rest. Others might use additional vendors for certain plan functions such as compliance testing support, employee communications, or plan auditing. Therefore, even if you observe “Paychex” in an HR context and “Fidelity” in your participant portal, you should still verify which entity is responsible for each action in the specific plan you are enrolled in.
When savers search for Paychex 401k Fidelity, the underlying question is usually: “What investments will I actually be able to choose?” Recordkeeping platforms can be user-friendly, but the good outcome is driven primarily by the menu of funds and their expenses, diversification, and suitability for your goals.
An objective evaluation focuses on:
Industry oversight reinforces the importance of comparing costs. Under U.S. retirement plan disclosure regulations, sponsors generally must provide fee information, and participants can typically request and review relevant documentation.
To evaluate investment choices effectively, it’s useful to understand common categories you may see in a Fidelity-hosted menu, and what you should look for in each category.
1) Index funds (e.g., U.S. equity index, international equity index, U.S. bond index)
Index funds typically aim to replicate a benchmark rather than beat it. When evaluating them, the most actionable items are the fund’s expense ratio, the diversification it provides (which index it tracks), and any differences in trading costs or implementation details described in the prospectus. You should also check whether the plan uses separate share classes for retirement participants that may carry different expenses than the public mutual fund.
2) Target-date funds (TDFs)
Target-date funds automatically adjust asset allocation over time based on a target year. For participants, the key question is not “Is it a TDF?” but “How does the TDF reduce risk as the target year approaches?” Many plans present a glide-path chart or provide descriptions of the fund’s shifting exposure to equities, bonds, and sometimes cash equivalents. You should also check the expense ratio and the underlying holdings (e.g., whether the TDF invests in index funds, in-house funds, or a combination).
3) Stable value or money market-like options
Some plans include stable value funds or conservatively managed options meant to reduce volatility. These can be attractive for participants who need liquidity or who want a defensive allocation. However, you should understand the withdrawal provisions (e.g., restrictions on timing, redemption limitations, surrender charges, or book-value accounting rules if described). Stable value rules differ from plan to plan.
4) Company stock (if applicable)
If your plan offers employer stock, there can be unique tax and diversification considerations. Even if it’s available, you should review whether shares are held in a trust or through a brokerage window, and whether there are transfer restrictions. Many participants benefit from understanding that company stock is concentrated risk, and plan-level concentration rules or brokerage restrictions can affect how quickly you can rebalance.
5) Managed accounts or participant advisory features (if offered)
Some recordkeeping platforms allow participants to select managed solutions (e.g., automated allocation or advisory programs). These can be helpful, but they often carry additional fees. If your plan offers these features, check the exact fee structure and understand what happens when your personal inputs change.
Beyond fund selection, you should also check your plan’s default investment option (often used when you do not make an election). Many plans use a money market fund or a target-date fund as the default. If you were automatically enrolled, you should verify what your contributions were invested in from the beginning.
This is particularly relevant for employees who have just started working or who recently changed jobs. If you failed to make a timely election, your first contributions might have been directed to the default option. Later, you can typically make exchanges to align with your preferences, but the cost and timing of those trades should be considered.
Even when a plan is well-designed, implementation matters. In a workflow involving Paychex 401k Fidelity, a common practical concern is how quickly changes take effect and how payroll timing maps to plan transactions. Employees often want to know whether an enrollment or contribution increase will be reflected in the upcoming pay period.
To reduce uncertainty:
These are not merely “admin trivia.” The differences can influence short-term account growth and your confidence in the system’s reliability.
To understand how payroll integration affects you, it helps to consider a few scenario patterns that employees commonly encounter.
Scenario A: New hire enrollment
Suppose you start mid-month and your plan permits deferrals only after a specified eligibility date (e.g., after 30 or 90 days). HR might submit your eligibility status through the administrative system, and your first deferral might not appear until the next payroll file after eligibility begins. If you want to maximize the match, you should ask HR about the earliest effective date for contributions and about any waiting period.
Also ask: “If I enroll today, does it apply to the current pay period or the next one?” That question will reveal whether the system has cut-offs and how quickly enrollment data reaches recordkeeping.
Scenario B: Increasing contribution to capture the company match
Employees often raise their percentage in October or near year-end, hoping to secure a match. If their contribution increase misses the payroll cut-off for a particular pay date, the match calculation might not reflect it until later. Additionally, some plans might compute matching using payroll-based dates and/or might have special rules around eligibility and vesting. Even if contributions are made, the match may have a separate eligibility condition (for example, you must be employed on the last day of the plan year to receive certain match components—though that is plan-specific and must be disclosed).
Scenario C: Changing your investment elections
If you move from conservative funds to more aggressive stock funds, the key is the processing time. Most plans implement exchanges at scheduled times or at the next available trading window after receipt of your instruction. If you submit an exchange near cut-off, it might process a day or more later. For many long-term investors, this timing does not matter much, but for employees trying to time market events or hoping that “yesterday’s drop” will be reflected immediately, it can be frustrating.
Scenario D: Taking a loan or planning a distribution
Loans and distributions add operational steps: forms, verification, and sometimes waiting periods. If your plan uses Fidelity for recordkeeping, Fidelity might host the loan process, but the employer’s payroll system must implement loan repayments through payroll deductions. That means there is a coordination point between the payroll administrator and recordkeeper. Employees can reduce confusion by asking HR and Fidelity support what to expect for the first payroll deduction and the expected posting date of the loan.
In short, for Paychex 401k Fidelity setups, your operational homework is worth doing early. When you understand the timeline, you can plan decisions (like enrolling, increasing contributions, or scheduling a rollover) without relying on guesswork.
Participants frequently ask for “price information” when evaluating retirement options. However, fees for 401(k) plans can vary widely depending on the plan size, negotiated arrangements, plan sponsor decisions, the investment lineup, and the fee allocation methodology. Without your plan’s specific documents, it would be speculative to state exact numbers.
Instead, an expert approach is to focus on the documents you can verify:
From a regulatory standpoint, U.S. retirement plan fee and service disclosures are commonly linked to rules under the Employee Retirement Income Security Act (ERISA) and related Department of Labor guidance. For background, the U.S. Department of Labor (DOL) maintains resources on retirement plan disclosures and fiduciary standards.
To make fee comparisons more practical, you can think of plan costs in two layers:
Layer 1: Plan-level and recordkeeping/administrative costs
These may be charged in ways that are not obvious. For example, a recordkeeping fee might be paid by the plan’s assets and thus reduce the net investment returns of the entire plan or certain share classes. Alternatively, it may be charged via a dedicated fee schedule or fund-level expenses. If the plan-level fees are embedded into certain investments, your statement might not show an item called “recordkeeping fee.” In that case, you need to use the fee disclosure documents to understand the cost.
Layer 2: Fund-level expenses
These are often expressed as expense ratios and are typically paid continuously by the fund. If your plan invests in multiple funds with different expense ratios, your all-in cost will reflect the weighted mix of those funds over time.
Because participants often only see a high-level number (“expense ratio” or “fees”), it’s helpful to calculate an approximate all-in cost using the investment allocations you actually hold. Even a rough estimate can help you prioritize decisions.
Here is an example of how cost thinking works:
Your fund-level expense would be approximately (0.60×0.05%) + (0.30×0.10%) + (0.10×0.20%) = 0.03% + 0.03% + 0.02% = 0.08% per year (ignoring other plan-level items). Then you’d add any recordkeeping costs allocated through the plan. That’s why recordkeeping and investment expenses should be evaluated together.
Also consider that sometimes a plan includes higher-cost funds but also offers a lower-cost target-date option or a brokerage window. If you intend to use the target-date fund as a long-term default, its expense ratio might matter more than the expense ratios of individual funds you never plan to use.
Finally, keep in mind that fee disclosures can sometimes be updated annually, and investments can be replaced over time. It’s important to review your plan’s changes each year rather than assuming your fee structure is fixed forever.
Since Paychex 401k Fidelity often implies a participant-facing recordkeeping system, service experience becomes tangible. Consider:
Service experience is not a substitute for investment quality or fees, but it affects your ability to manage the plan responsibly over time.
In a well-run system, your online account should let you do the following efficiently:
If a participant cannot reliably interpret their statement, they may not detect errors. Therefore, service experience is also a practical risk control. If your portal shows “pending” transactions, you might be able to reconcile them quickly. If it does not, you may have to rely solely on HR, which can slow down resolution.
When evaluating digital access, consider security and usability too. A good account portal provides multi-factor authentication, helps you reset access safely, and provides clear confirmation when you execute transactions. While that might seem obvious, account usability is a major factor in participants’ ability to stay engaged with retirement planning.
Employees can unintentionally create avoidable risks when using a retirement system they don’t fully understand. Common pitfalls relevant to participants navigating Paychex 401k Fidelity include:
In other words, the very important feature of a retirement system is often not the interface—it’s whether it is predictable and governed by clear rules.
Let’s expand some of these risks and how to control them with concrete habits.
1) Timing risk (the “cut-off” trap)
To control timing risk, do not wait until the last minute when making changes intended to capture matching contributions or execute a major portfolio switch. Instead, learn the cut-off date and submission deadline for your plan. If you’re planning for a year-end match, start earlier than you think you need to. If your plan is built around payroll files, a delay of one pay period can materially affect results.
2) Administrative risk (assuming your actions were processed)
When you submit changes on a portal, ensure you receive a confirmation (a confirmation number, a timestamp, or a screen that clearly shows the new election). Then monitor your statement or transaction history to confirm the change processed correctly. If you don’t see it in a reasonable timeframe per plan rules, escalate quickly.
3) Beneficiary risk (the “outdated form” problem)
Beneficiary designations sometimes change during major life events: marriage, divorce, birth of a child, death of a named beneficiary, or changes in relationships. Many employees remember to update after one event, but then forget to revisit later. A good habit is to set a reminder annually or after major life events to confirm your beneficiary.
Also, if your plan offers spousal protections or has specific rules related to required minimum distributions or qualified joint and survivor options (for certain distribution forms), beneficiary designations can interact with distribution elections. This is another reason to keep documents updated.
4) Rollover risk (job change surprises)
When you leave your job, the rollover pathway matters. Some distributions are eligible for direct rollover to an IRA, while others might involve withholding or distribution timing rules. If you withdraw money instead of rolling it over, you might create tax and penalty consequences. If you roll to another plan, you must follow that receiving plan’s acceptance rules. Because these rules can be complex, it’s wise to confirm the exact instructions on the distribution paperwork and ask questions before initiating.
5) Investment risk (default options and inertia)
Many employees start in the default option and then forget to make an intentional choice. Default options are not necessarily bad, but they may not align with your risk tolerance or time horizon. A simple control is to revisit your investment elections periodically—especially after enrollment, after receiving new match instructions, or after a major life change.
Additionally, check whether the plan offers a Roth 401(k). Your investment returns are only one piece; your tax treatment (Traditional vs. Roth) can be equally important. If you don’t understand Roth eligibility or rules in your plan, ask HR or review plan materials.
Finally, remember that the biggest controllable risk is often contribution adequacy: not contributing enough. While this is not “Paychex vs. Fidelity” specific, a participant can mistakenly set a low contribution and never adjust it upward. If you are financially able, consider increasing contributions gradually over time, especially when raises occur or when you want to capture additional matching.
From an industry viewpoint, recordkeeping providers influence operational quality: contribution timing, transaction processing accuracy, and the availability of participant education. The DOL and other oversight bodies emphasize that plan fiduciaries must consider costs and services when selecting recordkeepers, consistent with ERISA fiduciary obligations.
Therefore, when you see Paychex 401k Fidelity, you can reasonably interpret it as: your employer’s 401(k) program likely uses a combination of administrative and recordkeeping services. Your job as a participant is to translate that structure into practical decisions—what investments you can access, what you pay, and what rules govern your actions.
To understand why recordkeeping details can matter, consider the participant’s lifecycle within the plan:
If recordkeeping functions are weak, participants experience delays, confusion, or error corrections. If recordkeeping functions are strong, participants can monitor and manage their accounts with confidence.
That doesn’t mean all outcomes are perfect—any large system can have occasional issues—but it means that recordkeeping quality directly affects your day-to-day ability to contribute, rebalance, and make decisions. When reviewing your plan, look for evidence of operational reliability: consistent posting of contributions, clear transaction records, easy investment exchanges, and supportive customer service.
The following supplemental material is designed to help you compare your situation objectively. It does not list any links, and it assumes you have access to your plan documents (SPD, Summary of Fees, and/or plan website disclosures).
| Assessment Area | What to Check in a Paychex–Fidelity-Style Setup | Typical Conditions/Requirements |
|---|---|---|
| Recordkeeping responsibility | Confirm which entity maintains your participant account and processes investment trades. | Your SPD or plan website should state the recordkeeper and administrative contact details. |
| Contribution timing | Determine when payroll contributions post and when they are invested per plan rules. | Payroll cut-off schedules and plan processing timeframes apply; enrollment changes may have a delay. |
| Fee structure | Identify both administrative/recordkeeping fees and fund-level expense ratios. | Fee disclosures and investment fund documents provide the verifiable amounts and how fees are charged. |
| Investment lineup | Compare options (index funds, TDFs, stable value, and any managed accounts if offered) for expense and diversification. | Plan committee decisions determine menu; eligibility for certain funds may depend on age or plan rules. |
| Transaction rules | Review exchange cut-off times and limits (e.g., number of exchanges per period). | Cut-off times are often tied to payroll and trading schedules; verify in plan documentation. |
| Loans and hardship distributions | Check whether loans and hardship distributions are available and what conditions restrict them. | Loans typically require repayment terms; hardship rules require qualifying events and documentation. |
| Rollovers on job change | Confirm rollover eligibility and whether “in-service” options exist. | Rules vary by plan; rollover instructions depend on plan terms and IRS requirements. |
| Beneficiary designations | Verify how to update beneficiaries and when changes take effect. | Beneficiary forms and effective dates are governed by plan rules; some changes require confirmation. |
Source (for background, not plan-specific pricing): U.S. Department of Labor resources on retirement plan disclosures and fiduciary responsibilities under ERISA, which inform how costs and services must be considered and disclosed in employer-sponsored retirement plans. For general regulatory context, participants can also consult official federal guidance on participant disclosures and fee information.
While the table above focuses on core plan mechanics, many participants also benefit from expanding the “what to check” list into a practical checklist they can use when they log into their account portal or meet with HR. Below are additional items that are frequently overlooked but can prevent operational problems.
| Additional Checklist Item | Why It Matters | What You Typically Look For |
|---|---|---|
| Roth vs. Traditional allocation | Determines tax treatment of future withdrawals. | Whether your plan allows Roth deferrals; any Roth eligibility rules; conversion or recharacterization constraints (if described). |
| Employer match formula | Helps you target the correct contribution rate. | Match rate, match cap, eligible pay type, vesting schedule references. |
| Vesting schedule | Controls how much employer money you keep if you leave. | Cliff or graded vesting schedule; vesting milestone timing. |
| Default election rules | Prevents “set and forget” mistakes. | Default fund; effective date for default allocations; how long default applies. |
| Required minimum distributions (RMDs) | May affect timing and distribution options later. | Plan’s RMD procedures; how Fidelity administers RMDs; any in-plan distribution options. |
| Qualified Domestic Relations Order (QDRO) handling | Can affect account access during divorce. | How the plan processes QDROs and timelines for review. |
| Reporting and tax forms | Ensures your taxes are accurate at year-end. | Availability of tax forms; Roth reporting; withholding reporting (if applicable). |
Use this sequence to build a defensible, objective understanding of your plan—especially when Paychex 401k Fidelity appears in HR communications or plan documentation.
Look for the entity that holds your participant account and executes contributions and investment transactions. If Fidelity is the recordkeeper, ensure the interface you use is truly connected to your employer’s plan.
Practical sub-steps:
Gather the SPD, fee disclosure documents, and any plan website disclosures. If you have questions, route them through HR or the plan help channel to avoid misunderstanding from informal sources.
Practical sub-steps:
Tip: if you ever see conflicting information between an HR summary and the SPD, treat the SPD as authoritative and ask HR to reconcile the discrepancy.
Check:
Practical sub-steps:
Separate costs into two buckets:
Then compare options within your plan menu using the verified expense information you find in the documents.
Practical sub-steps:
Choose investments based on diversification, risk tolerance, and expected time horizon. If target-date funds are available, review glide-path assumptions and underlying holdings philosophy as described in plan materials.
Practical sub-steps:
Review exchange rules, loan rules, distribution steps, and any requirements that affect timelines—particularly if you anticipate changing jobs.
Practical sub-steps:
Confirm beneficiaries, update contact information, and ensure contribution elections reflect your current goals. Re-check after major life changes.
Practical sub-steps:
It typically indicates that your employer’s 401(k) program may involve Paychex for certain administrative functions and Fidelity for recordkeeping and participant account services. The exact responsibilities depend on your specific plan documents.
To avoid uncertainty, look at where you manage transactions. If your participant portal is hosted through Fidelity and shows your balances and fund allocations, that strongly suggests Fidelity is the recordkeeper. If enrollment is initiated through HR but then reflected in Fidelity, that suggests Paychex (or HR using Paychex) supports administrative processes while Fidelity supports account administration.
No. Recordkeepers can provide competitive pricing, but plan costs also depend on the employer’s contract terms, plan size, fee allocation methodology, and the investment lineup. You should review your plan’s disclosed fees and fund expense ratios.
In some cases, recordkeeping fees are negotiated and allocated through plan assets. That means participants don’t see them directly but they still impact net returns. The fee disclosures you receive (or can access via the plan’s materials) are the best way to know the true cost.
Your Summary Plan Description (SPD), Summary of Fees, and official plan disclosures on the participant portal (or from HR) are generally the very authoritative sources. Avoid relying on informal guidance for time-sensitive decisions like distributions and rollovers.
When you’re making a time-sensitive decision—such as initiating a distribution due to leaving your job—use the official instructions from the plan and recordkeeping portal. If your situation is complex (for example, you need multiple distributions, or you’re dealing with taxes in more than one state), ask for written confirmation or request a call with plan support.
Check your plan’s enrollment and payroll timing rules in the SPD and the plan website disclosures. Contribution cut-off dates and processing schedules can affect how soon a change is reflected.
Practical approach: after you submit an election, check your transaction history and confirm that the next pay period contributions reflected the new deferral percentage. If the change does not appear, compare the submission date to the cut-off described in the plan materials.
Often, yes—subject to plan rules and IRS requirements. Specific options (rollover to an IRA vs. another employer plan, timing, and eligibility) vary, so confirm details in your distribution paperwork and official plan instructions.
It’s important to distinguish between:
Your plan paperwork should specify which method is available and what the withholding rules are if you choose an indirect rollover.
Many plans allow exchanges but may impose cut-off times or limits on the frequency of exchanges. Review the plan’s transaction rules to avoid delays or failed transactions.
Also consider whether there are blackout periods or trading windows tied to recordkeeping updates. Some platforms process trades only on certain days, which can affect how quickly your exchange takes effect.
The platform itself typically has a second-order impact compared with the investment options and costs. However, platform usability can materially affect your ability to manage contributions and rebalance appropriately, which indirectly influences outcomes.
For example, if the portal makes it easy to adjust your deferral percentage after a raise or to switch funds without confusion, you may be more likely to maintain a long-term plan. Conversely, if transactions are difficult and you miss key steps, you might end up with suboptimal allocations.
Contact the plan support channel or your HR representative promptly and request a transaction history review. Keep documentation such as pay stubs and screenshots of transaction confirmations if available.
In your follow-up, ask for the exact status of the transaction: received, pending, posted, or corrected. If something is delayed, ask when the correction is expected and whether any retroactive adjustments will occur.
When you approach Paychex 401k Fidelity as a structured retirement program rather than a brand comparison, you gain clarity. Focus on verifiable plan details—recordkeeping responsibilities, contribution timing, disclosed fees, investment menu costs, and operational constraints. That objective method helps you choose actions that are consistent with your financial goals and reduces the likelihood of administrative surprises.
If you want, share the names of the funds listed in your plan and the fee disclosures you see (you can redact personal information). I can help you interpret what those documents imply for cost, diversification, and realistic next steps—without making assumptions beyond the text you provide.
To close with a participant-friendly “next actions” approach, here are concrete steps you can take regardless of whether you prefer an index-only approach, a target-date fund approach, or a blend:
That sequence converts “brand names” into a plan you understand—so your contributions and investment decisions become deliberate, not accidental.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
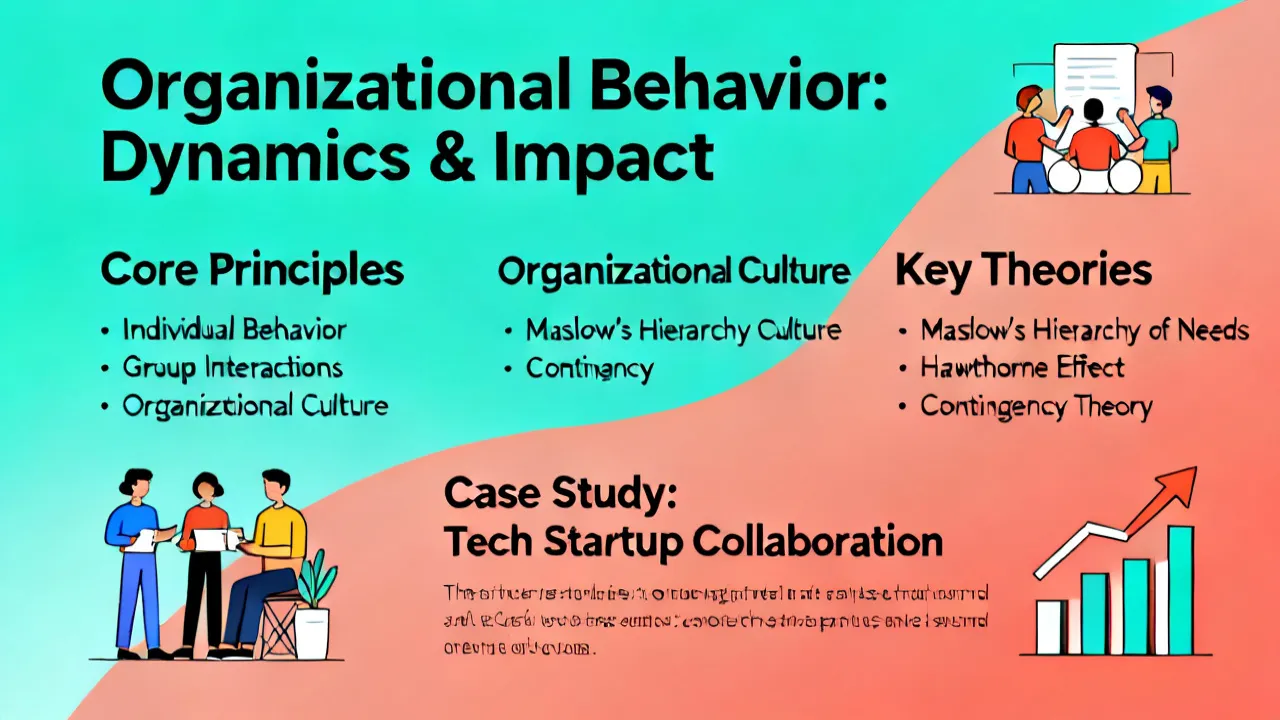
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.