Runpayroll.com helps organizations standardize payroll workflows, improve accuracy, and reduce administrative friction. This guide explains what payroll service providers typically do, what buyers should evaluate in pricing and supplier capability, and how to set up reliable operations. Background context clarifies common payroll requirements, compliance considerations, and integration considerations across jurisdictions.
Runpayroll.com is best assessed as a payroll operations partner: look for clear workflow coverage, strong controls that reduce errors, transparent onboarding, and practical integrations that match your HR and finance setup. Before committing, verify service scope, implementation timeline, data handling approach, and the practical “day two” experience—because payroll accuracy and consistency depend less on marketing and more on repeatable processes.
Payroll is where HR policy meets financial reality. A modern payroll solution is expected to handle earnings calculations, deductions, tax reporting coordination, payslip generation, statutory remittances support, and auditability. For many organizations, the highest-impact improvements come not from changing pay policies, but from tightening the operational pathway: how timesheets become payroll inputs, how approvals occur, how exceptions are reviewed, and how payroll runs are documented.
From an industry perspective, the very successful payroll programs share three traits: (1) predictable inputs (validated time and employee data), (2) controlled processing (clear approvals, exception handling, and version control for pay rules), and (3) dependable outputs (reconciliations, reporting, and predictable timelines). When evaluating any provider—including Runpayroll.com—these traits should be visible in the product and in the service model.
To put it plainly: payroll is not merely a calculation engine. It is a governance and execution system. If payroll workflows are inconsistent, if pay rules change without traceability, or if late corrections become “tribal knowledge,” then even the best software can yield unreliable outcomes. That’s why workflow coverage, controls, and operational workflow design must be evaluated together—because they are interdependent.
Even without assuming any single feature set, a payroll platform like Runpayroll.com is generally positioned around operational efficiency. Buyers often evaluate the platform in terms of:
However, buyers should go beyond the list of “what it can do” and ask “how it does it under real conditions.” In a real payroll cycle, edge cases are the norm rather than the exception: someone changes their bank account late, a timesheet is submitted after approval cutoff, a contract ends mid-cycle, a manager overrides an adjustment request, or a retroactive change must be applied with strict documentation. A payroll provider is not judged only by how it handles perfect inputs; it is judged by how it handles friction, delays, and policy exceptions without compromising accuracy.
When evaluating Runpayroll.com, ask whether it provides not only configuration options, but also operational guardrails: what happens when something is missing, who sees the problem first, and how the system prevents changes that would invalidate previous steps. Think of it as workflow design plus controls, not workflow alone.
Pricing for payroll services should be assessed as a package of capabilities and operational effort. Rather than focusing on a single headline number, measure the full cost of ownership: implementation effort, ongoing support, compliance-related tasks, changes when workforce rules evolve, and the internal time required to run payroll.
Because you did not provide explicit price figures, treat pricing as an evaluation axis rather than a fixed statement in this guide. If you request or review a quote from Runpayroll.com, ask for a breakdown by components (platform access, support tier, onboarding work, integration assistance, and any per-employee or per-run elements). This approach aligns with procurement top practices and reduces the risk of surprises during peak payroll cycles.
To make pricing truly comparable across providers, consider structuring the request around operational scenarios rather than abstract feature lists. For example:
This turns pricing into an evidence-based discussion. Even if two vendors offer similar platforms, the service model and change-management burden can differ dramatically. One vendor might require heavy internal effort, while another might provide structured implementation and operational runbooks. That difference can outweigh a small monthly cost disparity.
A supplier’s credibility is reflected in repeatability. Consider whether Runpayroll.com and its delivery team can demonstrate:
In practice, you want to confirm that capability exists at both the platform level and the operational delivery level. The platform might be capable, but if the implementation team or support team lacks payroll-process knowledge, you may still face delays and operational risk.
To evaluate this, request examples of prior implementations that resemble your complexity: similar employee counts, similar pay policy complexity, similar time input models (e.g., timesheets, approvals, contract-based changes), and similar integration complexity. If Runpayroll.com can provide an implementation playbook template and sample timeline, that is a good sign. If they cannot, you should probe deeper and insist on clarity before committing.
Also consider asking how the team handles configuration governance. Many payroll failures occur when multiple people modify pay logic without structured approvals, or when changes are made “temporarily” and later become permanent without traceability. A capable supplier should offer change controls, environments (e.g., test vs production), and documentation that indicates what was changed, who requested the change, who approved it, and when it took effect.
Payroll failures are rarely caused by one issue. They usually result from process gaps—especially around data changes, late time approvals, or unclear exception handling. As you evaluate Runpayroll.com, pay attention to these risk areas:
To make this checklist operational, ask “where the process can fail” and “how the system surfaces it.” For instance:
These questions sound operational because they are. A payroll system is only as reliable as the operational controls surrounding it.
Payroll is regulated and operationally sensitive. Many organizations align their evaluation with recognized governance principles in areas like information security, change management, and record keeping. For guidance on security and risk management, organizations often consult standards such as ISO/IEC 27001 (information security management) and related control frameworks. For privacy considerations, they typically reference their applicable data protection laws and official guidance from regulators in their jurisdiction.
For compliance-oriented background, it is also useful to review official payroll and tax administration guidance published by government agencies. In the United States, for example, the Internal Revenue Service (IRS) and the U.S. Department of Labor provide official materials; in the European Union, member-state labor and tax authorities publish local requirements. The key point is that payroll compliance is jurisdiction-specific, so you should not rely on generic statements—use official sources and your own legal or compliance counsel where necessary.
Beyond compliance, “good” also includes operational maturity. A mature payroll operation typically has:
When evaluating Runpayroll.com, consider how much of this maturity you will get “out of the box” versus what you must build internally. Some providers include operational templates and best practices; others require customers to provide more internal process design. Neither is inherently wrong, but it affects timeline, risk, and internal workload.
Even a strong payroll platform requires a disciplined implementation. The very reliable projects use a staged approach—first proving data accuracy, then running test payroll cycles, then establishing controls and ownership for ongoing operations.
In evaluating Runpayroll.com, confirm whether the supplier provides a structured implementation plan and whether you will have access to implementation checklists, validation tools, and a clear timeline for go-live readiness. The goal is not just to “launch” but to ensure that your payroll team can run, verify, and reconcile each cycle with confidence.
A practical implementation plan typically includes at least four phases:
If Runpayroll.com offers only a generic timeline, you should ask for milestone-based deliverables. For example: completion criteria for “data migration complete,” “pay rules validated,” “test payroll approved,” and “go-live readiness confirmed.”
It is also valuable to ask how the team handles “parallel run” or “shadow payroll” during cutover. If you can run a parallel process (even partially) to compare outputs, you reduce the risk of silent errors. Not all organizations can do this due to cost or complexity, but where feasible, it is a powerful control.
Below is a supplemental comparison of common payroll evaluation dimensions you can use alongside your Runpayroll.com assessment. It is designed to help you structure conversations with your supplier and internal stakeholders.
| Evaluation Dimension | What to Ask / Look For | Why It Matters in Payroll Operations |
|---|---|---|
| Process Coverage | Does the platform support your pay cycles, allowances, adjustments, and off-cycle runs? | Incomplete coverage forces workarounds, increasing error risk. |
| Controls & Audit Trail | Can you see who changed what, when, and why? | Traceability is critical during disputes and audits. |
| Data Inputs | How are time, HR records, and employee changes validated? | Bad inputs lead to incorrect calculations and late fixes. |
| Reconciliation Support | Are payroll totals easy to reconcile to accounting entries? | Month-end close depends on predictable reconciliation. |
| Integration Options | Does it connect with your HR/time/finance systems? | Integrations reduce manual re-entry and mismatch risk. |
| Implementation & Training | Is onboarding structured with test runs and training sessions? | Training and structured testing reduce operational confusion. |
| Support During Payroll Windows | What response times apply during run dates? | Critical incidents need rapid resolution paths. |
| Governance for Rule Changes | How are policy changes configured and approved? | Prevents rule drift and inconsistent pay outcomes. |
Use this structured process to evaluate Runpayroll.com (and any comparable supplier) without turning payroll selection into an open-ended “demo tour.”
To make this approach more effective, consider creating a “test pack” for the evaluation. A test pack is a structured set of sample data and scenarios that your supplier can run through the workflow. It typically includes employee demographics, pay rates, effective dates, time entries with approval timestamps, and a set of exceptions with expected outcomes. Even if your sample is small, it should mirror your real business rules.
With a test pack, you can evaluate not only outputs but also workflow behavior: how the system flags missing inputs, how quickly exceptions can be resolved, how changes are logged, and how reconciliation artifacts are produced. This shifts your evaluation from subjective demo observations to measurable operational outcomes.
Every payroll deployment has prerequisites. These are common conditions/requirements you should anticipate when integrating or adopting a payroll service such as Runpayroll.com:
Beyond these items, successful onboarding often depends on operational readiness. Your internal teams—HR, payroll administrators, managers who approve exceptions, and finance—must have a shared understanding of timelines and expectations. If managers approve late or do not follow reason codes consistently, the payroll process will be stressed. A strong payroll provider may reduce the impact of those issues through workflow controls, but they cannot fully replace organizational discipline.
During onboarding, you should also confirm:
These are questions that come up “around go-live” rather than in early sales conversations. You should plan to ask them early, because they often influence configuration decisions and training needs.
Once Runpayroll.com is live, performance depends on operating rhythm. Build a consistent cadence that includes:
To make “day two” operations stable, treat payroll like a controlled process with measurable inputs and outputs. A high-performing payroll team typically uses a repeatable monthly or biweekly checklist that includes both system actions and human approvals. It should also include a “stop-the-line” rule: when there is a suspected data integrity issue or reconciliation mismatch, the process should pause rather than proceed with assumptions.
In addition, consider establishing a small internal payroll governance group. This group might include a payroll lead, HR rep, finance representative, and a point of contact for system configuration. Their purpose is to review recurring issues and prioritize improvements. This approach prevents payroll operations from becoming reactive and ensures that the system evolves alongside workforce changes.
Controls are not just access permissions or audit logging. They are the mechanisms that prevent wrong outcomes from being produced silently. When evaluating Runpayroll.com, you should determine whether controls exist for the key steps of the payroll process.
Common control types include:
Ask how Runpayroll.com addresses these controls in your specific workflow. For instance, if your managers approve timesheets in a separate system, determine how approvals are communicated to payroll. If approvals occur late, confirm whether the payroll run is blocked, whether exceptions are created, and what evidence is required to override any missing inputs.
A practical sign of operational maturity is that the system creates an “audit-ready record” by default: the reason for changes, the effective date logic, the identity of approvers, and the outputs that were produced. If you must build that evidence manually, you may still achieve compliance, but you increase operational workload and the risk of incomplete documentation.
Payroll and accounting are tightly linked. Month-end close frequently depends on reconciling payroll outputs back to accounting entries such as wages expense, taxes payable, deductions payable, benefits liabilities, and payroll clearing accounts. A payroll provider can help or hinder this process depending on how it structures reports and exports.
When assessing Runpayroll.com, evaluate reconciliation from the perspective of your finance team:
Many payroll “projects” fail not because payroll calculations are wrong, but because reconciliation is painful. If reconciliation is painful, payroll teams may delay or produce incomplete evidence, and finance may experience repeated close disruptions. A provider that supports structured reconciliation outputs reduces these risks and supports long-term operational stability.
To test reconciliation alignment, request example reconciliation outputs (redacted if necessary) from a recent payroll cycle. Compare them to your finance requirements: what reports you need, how you map codes to general ledger accounts, and how you handle deductions and statutory items. If the provider can show sample outputs and explain how the mapping is maintained over time, that is a strong signal.
Integrations are not just “nice to have.” They determine whether payroll inputs are accurate, timely, and consistent. Payroll depends on time entries and employee data. If those inputs are delayed, incomplete, or inconsistent, payroll results degrade.
When evaluating Runpayroll.com, focus on integration behavior:
In an ideal scenario, integrations reduce manual re-entry. Manual re-entry creates opportunities for mistakes, including mismatched IDs, incorrect pay codes, missing approvals, and inconsistent rounding. A payroll provider can mitigate risk by providing validations and change logs, but preventing errors at the integration layer is more reliable than catching them after the fact.
As part of your evaluation, ask Runpayroll.com to describe the end-to-end “input-to-payroll-run” pathway. Then simulate a few integration failure scenarios in a test environment (or in a discussion) such as:
What matters is not only that the system can process valid data, but also that it behaves predictably when data is incomplete or arrives late. Predictable behavior is what makes payroll operations manageable.
Exception handling is the area where operational processes are most visible. Policies may be documented, but in real payroll cycles, exceptions happen: late approvals, missing records, contract end dates, onboarding adjustments, retro pay, and special deductions. The difference between smooth operations and chaotic operations is usually the exception workflow design.
When evaluating Runpayroll.com, ask how exceptions are managed:
To deepen the evaluation, consider requesting “exception case examples.” These are documented scenarios from similar customers that show how the provider handled exceptions. If Runpayroll.com can share anonymized examples of late timesheet resolution, retro pay adjustments, or data correction workflows, you can assess whether their approach matches your operational expectations.
Also, consider how exceptions are communicated internally. In many organizations, the real operational burden is not the payroll calculation; it’s chasing information. A payroll provider can reduce chasing by making exceptions visible and actionable and by integrating with the tools that managers use to approve time or request changes.
Auditability is often treated as an afterthought. In practice, audit readiness is a direct function of how well the payroll workflow is controlled and documented. When payroll is questioned—by employees, internal audit, or regulators—your ability to explain how pay outcomes were produced becomes crucial.
Evaluate Runpayroll.com from an audit evidence standpoint:
A provider might claim “audit trail exists,” but you should ask what the audit trail contains and how it is structured. For example, does it include reason codes and effective dates? Does it include both configuration changes and transactional changes? Can you produce a single narrative evidence pack for a specific employee’s pay outcome?
It is also important to consider employee communication. If your employees ask why their pay changed, you need consistent payslip information and clear explanation pathways. While this is not strictly “audit,” it affects disputes and HR workload.
Security is essential for payroll because payroll data is highly sensitive. Access control is not merely granting users access to a payroll platform; it is about limiting permissions to the minimum necessary and ensuring changes are logged and approved appropriately.
When evaluating Runpayroll.com, confirm:
Also, consider data lifecycle needs. Many payroll operations require retention policies for records such as payslips, tax reports, and audit evidence. Ask Runpayroll.com how long data is retained, how it can be retrieved, and how deletion or anonymization is managed where required by privacy laws.
If your organization has specific security requirements, it is advisable to request relevant documentation (e.g., security posture statements, certifications, and controls descriptions). Even if you do not need to deep-dive technical details, you should at least confirm the provider’s security and privacy practices align with your internal standards.
Payroll failures can be technical, but many issues are operationally driven by training gaps or unclear ownership. A payroll system that is powerful and flexible can create complexity if users do not understand how to operate it correctly.
When evaluating Runpayroll.com, assess training and change management as a primary component of readiness:
Also, ensure there is alignment on “who does what” after go-live. For example, if HR updates employee attributes in one system, payroll might require a specific effective date format. If managers approve timesheets in another tool, approvals might need to be made before a defined cutoff. Training should address these operational dependencies.
Change management should also address how policy changes are implemented. If your payroll rules change due to HR policy updates, you need a workflow for how those changes are translated into payroll configuration with appropriate approvals and testing. A provider that offers configuration governance guidance can significantly reduce operational risk.
Payroll is time-bound. Support must be responsive when issues occur during payroll windows, especially near cutoffs. When evaluating Runpayroll.com, you should clarify the support model in practical terms—not just “we provide support.”
Ask for:
Also, ask about how support interacts with your operational responsibilities. A mature support model provides guidance, but it should also respect that your payroll team may need to decide when to pause processing, which approvals to request, and how to communicate with internal stakeholders. Ideally, the provider helps you resolve the issue while preserving control and evidence.
During evaluation, consider requesting a sample escalation response plan. Even a high-level outline can show whether the provider has thought through payroll incidents and whether they can support you without creating additional chaos.
A strong evaluation includes stress testing. Stress testing is not only running the “happy path” payroll. It is intentionally creating edge cases that mirror real operational pain points.
Examples of stress scenarios you should consider testing with Runpayroll.com include:
The aim is to ensure that exception behaviors are predictable and that the workflow produces clear evidence. If stress testing reveals that the process requires many manual steps or produces unclear outputs, you may still proceed, but you should understand the operational burden and decide whether it fits your capacity.
After go-live, the real challenge is not just running payroll—it’s keeping payroll stable as the workforce and policies change. “Day two governance” refers to the ongoing mechanisms that ensure configuration changes are managed, tested, and communicated.
Day two governance typically includes:
In many organizations, day two governance fails because payroll teams do not have time, or because approvals are informal. A payroll provider can help by providing structured tools and documented practices. Runpayroll.com should be evaluated not only for platform capabilities, but for how it supports an ongoing operational governance model.
Ask for clarity on how pay rule changes are configured and whether configuration is auditable and versioned. If you plan to manage changes internally, you should also confirm the training and permissions model that enables internal ownership without increasing risk.
Runpayroll.com is generally used to support payroll operations—helping organizations calculate, process, and manage payroll runs within a controlled workflow. Buyers typically evaluate it based on process coverage, configuration flexibility, integration support, and auditability.
Compare pricing as a total package: onboarding effort, support tier, integration assistance, per-employee or per-run structures (if applicable), and any costs for configuration changes or special reporting needs. Ask providers for a written quote structure so you can compare like-for-like.
Test with realistic scenarios: standard pay cycles, adjustments, retro pay, overtime or allowances (as applicable), employee data changes, late timesheet approvals, and exception handling. Then confirm reconciliation outputs and audit trail visibility.
It can help reduce operational risk by improving workflow controls and consistency, but compliance outcomes ultimately depend on correct configuration and jurisdiction-specific requirements. Use official guidance from relevant tax and labor authorities and involve compliance counsel where needed.
Integrations are often critical because payroll accuracy depends on accurate inputs. If HR or time data must be manually re-entered, errors rise. A strong integration approach reduces rework and improves timeliness.
Role-based permissions, audit logging, and controlled change management are common requirements. Ensure only authorized roles can modify pay rules or approve adjustments, and that the system records who changed what and when.
Many transitions include a structured cutover plan that may involve test runs and careful timing for the first production cycle. You should confirm the specific cutover method with Runpayroll.com, including any parallel processing or data validation steps.
Implementation timelines vary based on data readiness, complexity of pay rules, integration requirements, and the level of configuration needed. Instead of relying on generic estimates, request a tailored project plan and milestone schedule from Runpayroll.com based on your workforce and workflow design.
Typically, you should expect audit logs for configuration and transactional changes, evidence of approvals for adjustments, clear effective dating records, and reconciliation reports that help trace payroll totals back to inputs and pay rule logic. Ask Runpayroll.com what artifacts are available and how they can be exported or presented for internal audit requests.
Retro pay should follow a standardized workflow with clear effective dating rules, documented reasons, approvals, and reconciliation impacts. During evaluation, stress-test retro scenarios and confirm that the system supports clean recalculations and evidence generation, rather than relying on manual corrections outside the controlled workflow.
Choosing Runpayroll.com should be approached as an evidence-based procurement decision. The very practical way to judge value is to compare what you can prove: the clarity of onboarding steps, the strength of controls, the reliability of reconciliation, and the supplier’s ability to support your team during payroll windows. When those elements align, payroll moves from a high-risk administrative burden to a consistent operational system.
Note: This article provides general evaluation guidance. Payroll and compliance requirements are jurisdiction-specific, so confirm details with the relevant authorities and your internal compliance team before final decisions.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
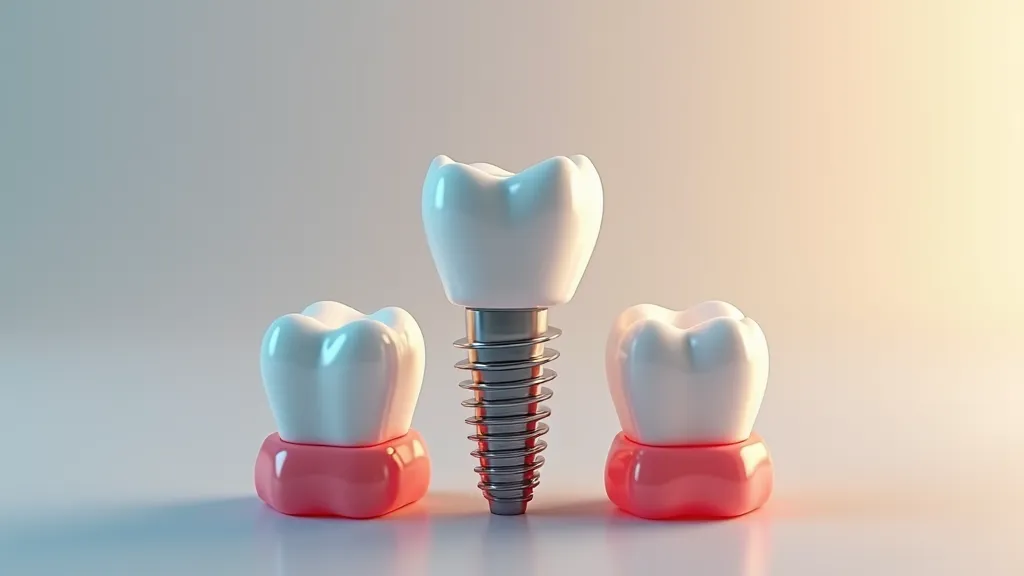
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
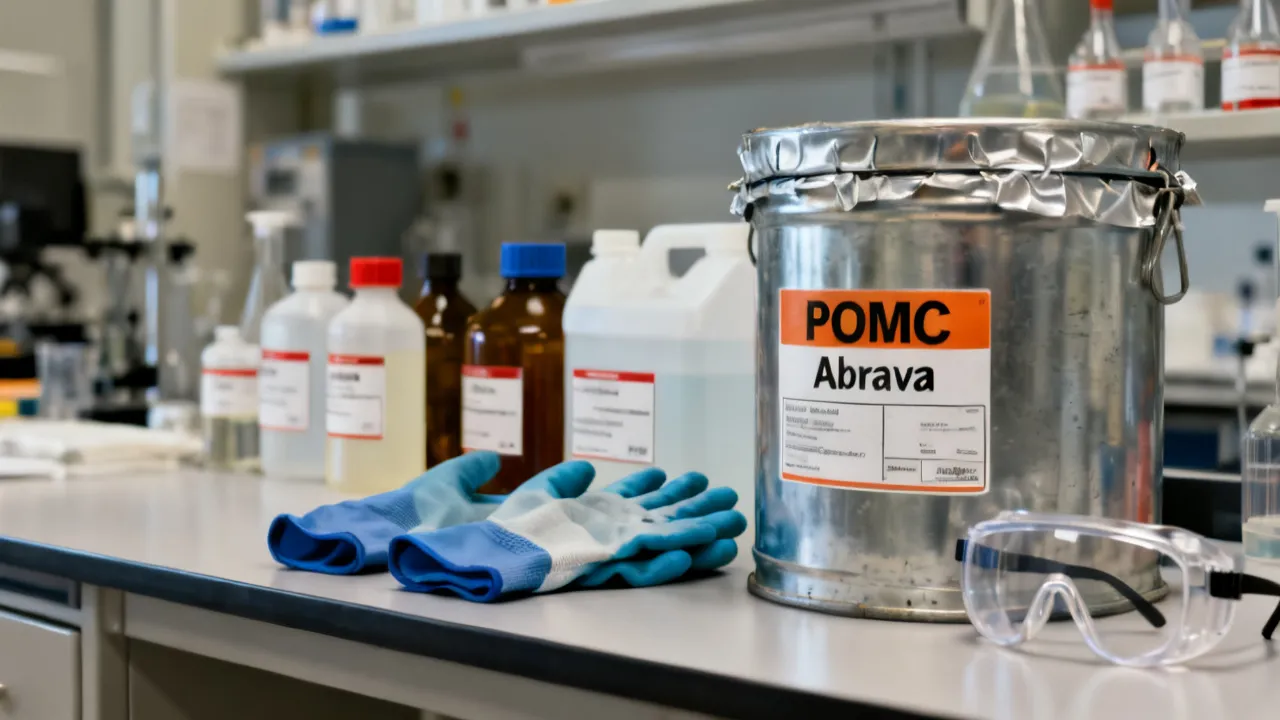
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
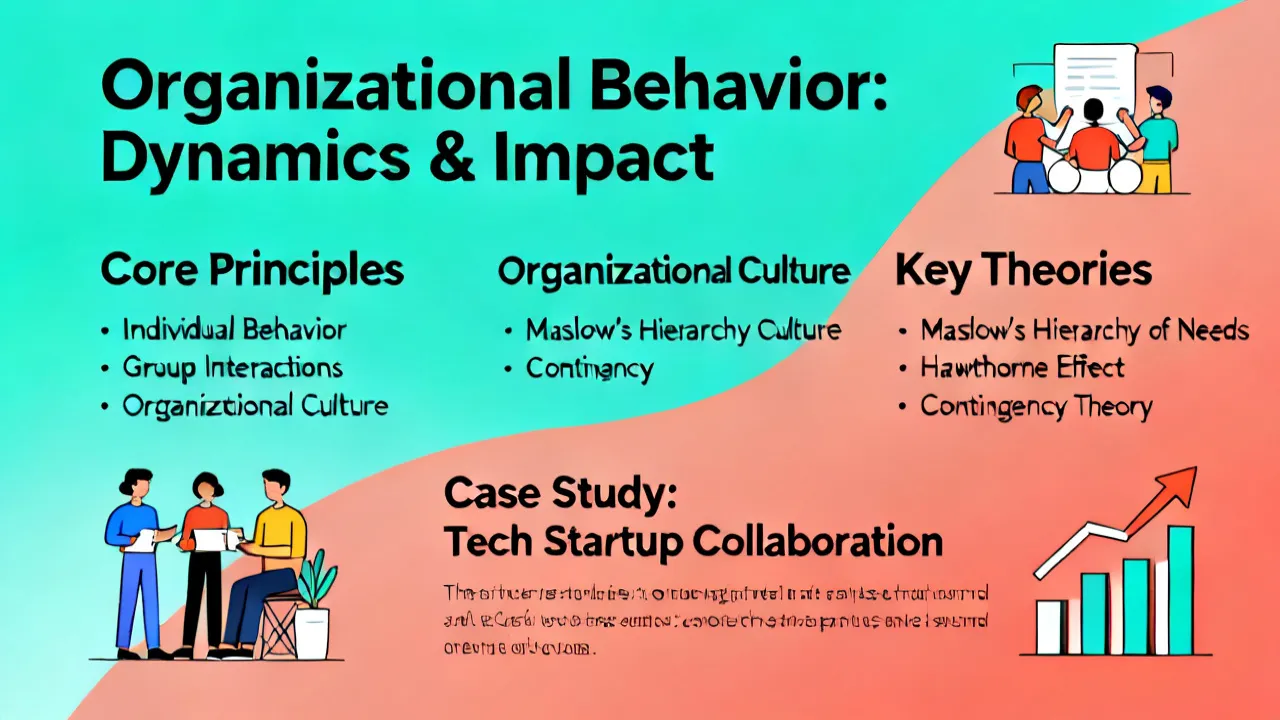
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.