SagPayroll streamlines payroll administration by connecting compliance-ready workflows with day-to-day processing needs. This guide explains what “Www.sagpayroll.com” represents in practice: payroll data capture, approvals, statutory reporting, and payrun readiness, using objective industry context around payroll governance, security expectations, and operational controls.
For organizations evaluating payroll administration platforms, the practical question is straightforward: can you run payroll consistently, maintain auditability, and handle compliance obligations without turning day-to-day operations into a bottleneck? Www.sagpayroll.com is often referenced by decision-makers seeking a structured approach to payroll processing—where employee data, approvals, and payment execution are governed through clear operational steps rather than ad-hoc spreadsheets.
From an industry perspective, payroll software is less about “features on paper” and more about how well it reduces error risk during pay runs, supports internal controls (such as approval chains), and provides traceability when exceptions occur—like corrected hours, leave adjustments, or payroll re-runs. A payroll platform can look complete in a demo, but the operational reality is shaped by workflow design, data integrity mechanics, and the discipline it brings to finalization and change control.
In many organizations, the real payroll challenge is not the basic calculation. It’s the final mile: the late edits, the “urgent” adjustments requested after approvals are already underway, the reconciliation work required by finance, and the need to explain payroll results if an employee or regulator asks “how did we get here?”. That’s where a reliable platform approach matters most.
Payroll is a high-impact business process. When payroll fails or is delayed, employee experience suffers immediately, and HR and finance teams must spend time on reconciliation and corrections. Because payroll touches both employee compensation and statutory obligations, organizations tend to prioritize:
Platforms referenced through Www.sagpayroll.com are typically evaluated against these pillars—especially by teams that want to reduce manual steps while maintaining oversight over calculations and payroll outputs.
Reliability also matters because payroll is time-bound. There is always a pay calendar, cut-off times for inputs, and downstream dependencies such as employee bank file generation, accounting posting schedules, and reporting deadlines. When systems or processes are inconsistent, the risk is not just incorrect pay—it's also missed deadlines, internal rework, and the erosion of trust in payroll outputs.
Moreover, in modern organizations, payroll reliability is tightly connected to employee engagement and brand perception. A single payroll mistake can drive a cascade of support tickets, HR time spent responding to employee concerns, and finance time spent verifying compensation components and deductions. Even when the “net mistake” is eventually corrected, the process friction can be severe.
When an organization explores a payroll service or software—often initial discovery begins with a domain like Www.sagpayroll.com—buyers usually compare how the solution supports core payroll lifecycle activities:
In mature payroll operations, reliability is achieved by combining correct configuration, controlled workflow, and monitoring—rather than only relying on the correctness of individual operators. When people become the system, errors increase under pressure. When the platform becomes the control environment, errors become less likely and more traceable.
As buyers examine platforms, they often discover a second-order concern: governance. The organization may have correct policies, but without platform support for approvals and traceability, policies become difficult to enforce consistently. A well-designed payroll system should make the “right way” the easiest way, and the “wrong way” harder to perform without detection.
Another recurring buyer concern is operational flexibility. Payroll is rarely uniform across all employees. There may be different pay structures, contractor vs. employee logic, different deduction types, or multi-location rules. If a platform handles complexity only through heavy manual intervention, it may not actually reduce operational risk.
Therefore, buyers evaluate not only whether pay can be calculated, but whether the platform can be operated safely by the actual team members, with the actual approval process, under real payrun pressure.
Payroll operations intersect with risk management. While there is no single universal “top practice” for every organization, the broader governance logic remains consistent across payroll and finance systems:
From an expert standpoint, these controls are often the determining factor between a payroll process that “works very of the time” and one that holds up under pressure—such as year-end adjustments, employee onboarding in the middle of a cycle, or correcting bank details before a pay date.
Consider a common operational scenario: a late update arrives after the payroll cut-off—such as an employee reporting incorrect hours or HR receiving confirmation of a backdated allowance. In a spreadsheet world, the correction might be done quickly “just this once,” but then the rest of the process is unclear. In a controlled platform environment, the correction should be captured as an exception, run through defined workflows, and produce traceable outputs that show the difference between original and corrected results.
Governance also includes how the platform handles “state.” Payroll systems often have stages—draft, in review, approved, processed, finalized. If a platform does not enforce these stages, users can accidentally apply changes to already approved payruns, weakening internal controls. Operational reliability requires the system to support states, locks, and audit logs that align with governance.
Finally, governance is not just internal. External compliance risk is influenced by whether employees receive correct information, whether deductions are calculated properly, and whether reporting can be generated with consistent logic. When governance is weak, compliance becomes harder because the organization cannot prove the calculation process or timing of changes.
Organizations often ask about pricing when they encounter references to Www.sagpayroll.com. Because pricing can vary by deployment model, number of employees, feature scope, and support requirements, it is top practice to treat any public number as conditional until a formal quote or contract scope is confirmed.
Rather than relying on broad estimates, a credible procurement approach evaluates TCO components such as:
If your organization receives price information during procurement, it should be assessed alongside these total cost drivers to ensure you understand the true cost of ownership over multiple payroll cycles.
It’s helpful to think of TCO in terms of operational labor. If a payroll system requires manual reconciliation every cycle, then the “software cost” may be low but operational cost may be high. Conversely, a system that reduces reconciliation time might have a higher subscription fee but lower overall labor cost. The real question is how many hours your team spends on each payrun stage: input preparation, validation, approvals, calculation verification, reconciliation, reporting, and exception resolution.
Another hidden TCO driver is the cost of time-to-fix. When a payrun exception happens, how quickly can your team identify the root cause, apply a governed correction, and produce updated outputs? Platforms that provide traceability and structured exception flows often reduce the time it takes to correct payroll results. That saved time is a tangible cost reduction.
In a careful evaluation, organizations build a baseline of how payroll currently consumes time and effort. They estimate time saved per pay cycle (for example, fewer manual corrections or faster approvals). When compared to implementation and support costs, this baseline helps procurement decisions become more objective.
Below is a practical supplement you can use while assessing solutions connected to Www.sagpayroll.com. It rephrases typical “additional important information” as a structured comparison table, a step-by-step guide, and explicit conditions/requirements—without relying on unverifiable claims.
| Evaluation dimension | What to check | Why it matters |
|---|---|---|
| Workflow governance | Whether the system supports approval chains, role-based actions, and controlled payroll finalization | Reduces errors by preventing unreviewed changes from reaching payrun outputs |
| Data integrity controls | Validation rules, change tracking, and audit trail capabilities | Improves traceability and speeds up reconciliation during corrections |
| Payrun exception handling | How adjustments are managed (e.g., re-runs, retroactive changes, correction workflows) | Protects employee trust and preserves payroll history integrity |
| Reporting readiness | Ability to generate payroll registers and reports required by internal processes | Supports finance and HR operations without manual rework |
| Security and access management | Role-based access, data protection practices, and secure handling of payroll records | Minimizes confidentiality and compliance risks for sensitive employee data |
| Implementation approach | Data migration plan, testing cycles, and training documentation | Reduces go-live risk and shortens stabilization time |
The user story behind a platform reference such as Www.sagpayroll.com often begins with a supplier evaluation. In professional procurement practice, buyers validate supplier credibility through:
Even if a provider is widely known or referenced in industry channels, the safest approach is to validate capabilities through a structured proof—because payroll systems are highly sensitive to configuration, workflow design, and operational readiness.
To make supplier evaluation more objective, organizations frequently use a “proof package” approach. Instead of only asking for a general demo, they request:
These steps turn a vendor conversation into an operational validation. The goal is to confirm not only calculation accuracy but also the end-to-end workflow integrity.
When implementing payroll platforms connected to a domain reference like Www.sagpayroll.com, organizations frequently face implementation realities that affect outcomes:
These considerations tend to matter more than minor cosmetic differences in user interfaces. Payroll reliability is measured in what happens during exceptions—because that’s where organizations discover gaps in governance.
To expand on implementation reality: data migration is often underestimated. Payroll systems depend on consistent identifiers and correct mapping of pay components. If employee identifiers change between systems or mapping of historical pay elements is incomplete, it can lead to incorrect pay calculations or reconciliation discrepancies.
Additionally, training must be role-specific. HR users may focus on onboarding, leave entries, and pay element assignments, while finance users focus on reconciliation, reporting, and verifying ledger postings. If training is generic, mistakes can appear later in the workflow. Exception workflows require even more role-specific training because they often involve decision-making under time pressure.
Implementation also includes monitoring. Early in rollout, many organizations run enhanced monitoring: verifying outputs after each stage, validating totals against a known baseline, and tracking issues with a rapid feedback loop to correct configuration or workflow steps. This stabilization period can significantly improve long-term payroll reliability.
Payroll systems often claim “compliance support,” but compliance is top treated as a responsibility shared between your organization and the provider’s configurable capabilities. In objective terms, what you should seek is:
Rather than assuming any system automatically ensures compliance, successful organizations set up an internal review process and validate outcomes through tests before official pay periods.
Compliance readiness also includes how the system handles legislative or policy changes over time. Even if the payroll engine is sound, organizational policies evolve: tax tables can change, deduction rules can change, and reporting requirements can be updated. A reliable payroll platform should support controlled updates with clear communication and traceability.
Operational compliance is not just about configuration; it’s about evidence. When regulators require documentation, or when internal auditors request proof, the organization needs to show:
When a payroll platform supports auditability, it makes this evidence gathering far easier, reducing compliance stress during high workload periods.
Payroll data is sensitive. When organizations evaluate solutions referenced via Www.sagpayroll.com, they should ask security questions that map to operational risk, such as:
For credibility, security discussions should be supported by documentation or formal security materials, rather than informal assurances.
Security expectations in payroll environments often go beyond “login and password.” Organizations typically need to understand:
Payroll is also a target for fraud and internal misuse. A platform’s ability to enforce approvals and separation of duties contributes to preventing unauthorized changes. Even with strong security controls, weak governance around payroll finalization can create vulnerabilities, such as a user being able to modify pay outputs without proper sign-off.
Organizations often mitigate this by ensuring that the platform enforces workflow states: once a payrun is approved, it should be locked in a way that requires a controlled exception path to change. That exception path should create an audit record and preserve payroll history.
To ground payroll governance expectations in widely accepted frameworks, many organizations align their controls with established guidance in information security and internal governance. For example, the following resources are commonly referenced when defining auditability, access control, and operational risk management:
These sources do not “replace” statutory rules, but they help explain why modern payroll operations emphasize controls, traceability, and access governance.
When buyers reference these frameworks during procurement, it typically becomes easier to ask precise questions. Instead of “is it secure?”, the organization can ask “what controls manage access and logging?” Instead of “does it support audits?”, the organization can ask “what evidence does it produce and how long is it retained?” This shifts conversations from subjective assurances to operational and evidence-based evaluation.
In internal governance terms, payroll reliability is often treated as a control environment: inputs must be accurate, approvals must be enforced, and outputs must be verifiable. The link between governance and reliability is direct: systems that support traceability reduce time to resolve issues and increase confidence in payroll correctness.
“Www.sagpayroll.com” is commonly referenced as a portal or entry point for payroll-related services or software information. In procurement terms, it is typically the place where organizations review capabilities, request demonstrations, or initiate discussions about payroll processing workflows.
In many evaluations, a vendor’s website functions as the beginning of a larger discovery process. Decision-makers usually follow up with product documentation, solution design sessions, and workflow walkthroughs that demonstrate how payroll operations work end-to-end.
Treat any stated price as conditional until you confirm the deployment model, employee range, included services, and implementation scope. Compare total cost drivers such as onboarding effort, support availability, and reporting needs—not only the monthly or annual fee.
Also consider what is not included. Some packages may include core payroll processing but exclude specific services such as data migration support, custom report development, or compliance configuration. The evaluation should map the full solution scope to internal timelines and payrun cycles.
Very teams prioritize workflow governance (approvals and role permissions), audit trails, exception handling (corrections and re-runs), and reconciliation support. A payroll system’s value shows very clearly when inputs change late in the pay cycle.
Operational reliability also benefits from automated validations. For example, validation rules can detect missing bank details, inconsistent pay element configurations, or abnormal deduction amounts before a payroll run proceeds too far. The earlier issues are detected, the less disruption occurs.
Typically, payroll platforms support correction workflows such as retroactive adjustments and re-runs. The key question is whether the system preserves traceability—who changed what, and how outputs reflect the correction history.
It’s also important to confirm whether corrections preserve original payroll history for audit purposes, and how the system communicates differences between original and corrected payslips. Transparent correction histories support employee trust and reduce HR burden.
Yes. Even with strong automation, organizations usually require internal review steps for pay elements, approvals, and final verification. The goal is to ensure inputs and calculations match your defined rules before payment execution.
Software reduces manual work, but internal review ensures alignment with policy, correct configuration for your organization, and compliance with internal sign-off procedures. The review process also catches issues like missing employee data, incorrect pay structures, or unexpected input changes.
Ask how access is controlled by role, whether audit logs track user activity, how data protection is handled for sensitive employee information, and what safeguards exist for backup and recovery processes.
To make security evaluation actionable, ask for examples of audit log events, how role permissions are managed (including who can approve), and how the platform prevents changes to already approved outputs without a controlled exception flow.
No single software tool can guarantee compliance in all contexts. Instead, compliance readiness depends on correct configuration, controlled rule updates, documented workflows, and internal validation. The provider should support these responsibilities through configurable logic and auditable outputs.
Compliance is a shared process. Even if a system applies tax rules, the organization still needs to ensure that employee data is correct and that workflow steps ensure proper approvals and correct reporting timelines.
Request workflow documentation, sample reporting outputs, implementation and testing plans, security documentation (or formal assurances), and a scoped proposal that clearly states included services and responsibilities.
Additionally, request a clear description of support coverage during payrun critical windows, including how issues are escalated and how urgent corrections are handled. This reduces uncertainty during go-live and during peak payroll times.
When teams reference Www.sagpayroll.com, they are usually searching for more than a payroll calculator—they want a system that improves reliability, supports approvals, and provides auditability through the full pay cycle. The professional way to decide is to evaluate workflow governance, exception handling, audit trails, security expectations, and total cost of ownership within a clear scope.
If you align your requirements to controlled processes and validate outcomes through test scenarios, the payroll platform you select becomes a dependable operational foundation—not a recurring source of late-cycle risk.
Ultimately, the goal is not simply to run payroll. The goal is to run payroll in a way that your organization can trust, explain, and audit—especially when the unexpected happens, because payroll rarely stays perfectly routine. When governance is designed into the workflow and traceability is built into the system, payroll operations move from a fragile process to a reliable one.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
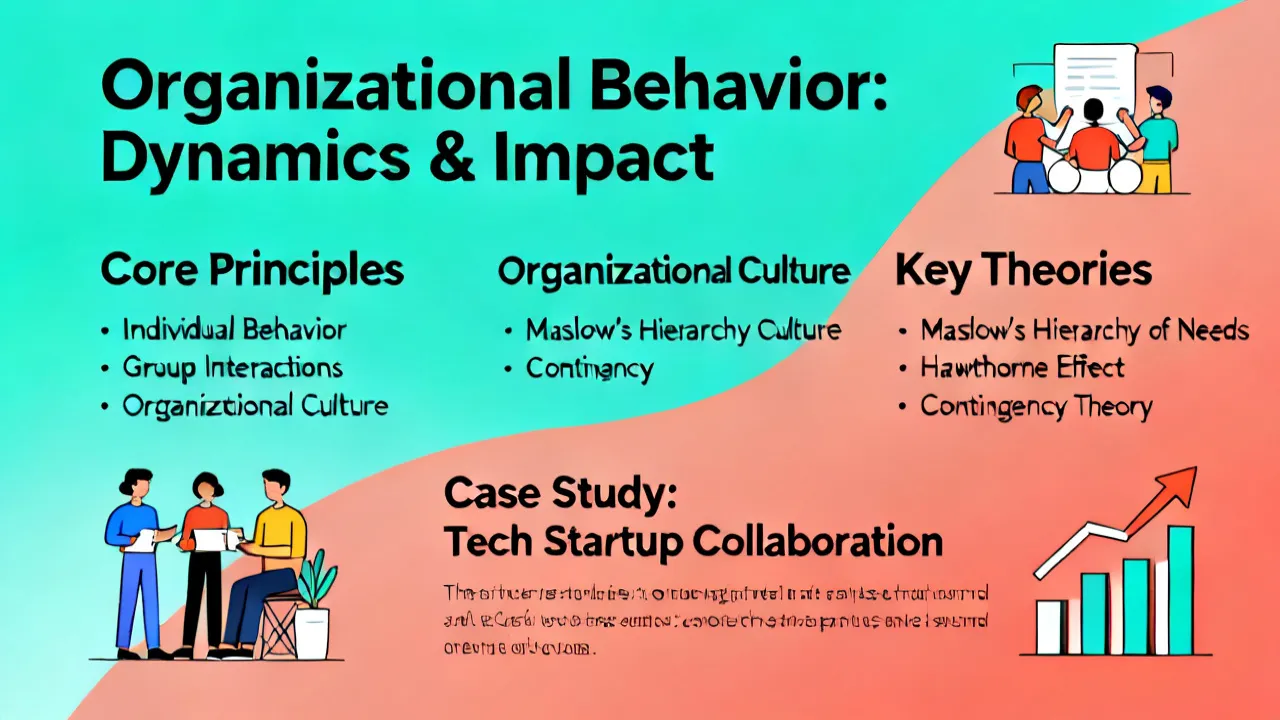
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.