This guide explains how Lifetime Benefits Solutions work and what to evaluate before choosing a plan. It provides an objective background on lifetime-value thinking, service longevity, and customer-support structures—covering what “lifetime benefits” typically means in practice, how suppliers differentiate offerings, and which requirements help reduce risk over time.
Lifetime Benefits Solutions are designed to translate good value into a structured promise—typically through extended coverage, durable service commitments, and clearer support pathways. Because these solutions vary widely by supplier and contract design, your first step should be assessing scope, eligibility rules, transferability, and how claims or service requests are handled over the long run. This guide takes an industry-oriented, objective approach to help you compare options based on requirements and conditions rather than marketing language.
When evaluating “lifetime” programs, the most important mindset shift is to treat them less like slogans and more like contracts with operational mechanics. A program’s real strength shows up in what happens after the purchase—when you submit a claim, when the original product is discontinued, when you move locations, when eligibility needs to be proven, and when a service partner has to execute the promise according to a shared standard. The supplier that has already designed those operational realities into the offering is usually the one whose “lifetime benefits” are most usable when you need them.
The phrase “lifetime benefits” can mean different things depending on the industry and the specific agreement. In professional contexts, the very reliable interpretation is not an absolute guarantee of outcomes, but a defined set of benefits that remain available for as long as stated in the contract terms (e.g., product ownership period, membership duration, or service lifecycle). For buyers, the key is to confirm:
From an industry-expert standpoint, the very mature suppliers clarify these elements in writing and align them with operational realities—inventory planning, staffing models, and service partner networks. The clearer the definition, the fewer “gray zone” disagreements will appear as your product moves from new condition into the longer, real-world period where wear, upgrades, and part availability become normal.
It also helps to think in terms of two layers of “lifetime.” First is the boundary of time: what period the agreement covers. Second is the boundary of performance: what level of service or replacement is promised. Some programs define “lifetime” as a long time but cap performance through exclusions, limitations, or replacement equivalency rules. Others define lifetime tightly but guarantee a broader service scope during that window. Understanding both layers upfront makes the eventual value assessment much more accurate.
Lifetime Benefits Solutions typically combine several components. Understanding the building blocks helps you evaluate credibility without relying on promotional claims. Most durable programs can be understood as a combination of:
When comparing suppliers, ask how their program handles disruptions—such as discontinued SKUs, relocation, changes in ownership, or increased demand. Suppliers that can answer these scenarios with clear rules tend to offer solutions that are easier to use later. A common misconception is that “lifetime” is mostly about duration. In reality, it’s often about continuity of service delivery despite the inevitable changes that occur over long periods: device generations shift, supply chains tighten or loosen, and customers’ circumstances change.
Strong suppliers often publish (or at least clearly provide upon request) a combination of service playbooks and eligibility scripts. This is especially important when claims are processed years after enrollment. If eligibility is computer-recorded and easily verifiable, your future self won’t be hunting for old proof in a stressful moment. If eligibility requires unusual documentation that can’t be reproduced easily, that’s a signal the program might be harder to realize later.
In many categories, you can also look for how the supplier handles “first time” versus “repeat” service. Some lifetime offerings cover a first repair but then treat subsequent issues differently. Others maintain consistent coverage but may require additional proof or may request that the same maintenance requirements be met. Either can be acceptable if clearly communicated—however, an unclear or inconsistent approach is a risk for customers.
Price is rarely “one number” in good solutions. It may appear as an upfront package fee, a bundled subscription, or a product-level premium. Even when you have a quote, the real question is whether the price corresponds to measurable commitments. Consider the following evaluation lens:
Industry note: In many sectors, “value” is top assessed through total cost of ownership and risk-adjusted reliability. This approach is consistent with established procurement and risk frameworks used in both public and private purchasing. A lifetime benefit program is essentially an insurance-like structure (even if it isn’t marketed as insurance), so you should evaluate it like a risk transfer instrument. That means you weigh not just the headline coverage but also how likely you are to use the covered items, how costly it would be if you were not covered, and what failure modes could leave you partially covered.
A practical way to make pricing comparable across suppliers is to model usage patterns. For example, suppose you anticipate a certain number of service requests per year. If Supplier A caps claims at one per year and Supplier B allows unlimited, the “lifetime” label becomes less meaningful than the operational cap. Alternatively, if your usage is low and you only need occasional assistance, a program with a lower premium and stricter caps may be rational. The key is to convert claims limits into expected cost and compare the “worst likely scenario” outcomes, not just the best case.
You can also ask how pricing changes over time. Some lifetime programs require annual administrative fees or require periodic renewals that the customer may not notice at first. Even if the program says “lifetime,” there may be conditions that keep you in good standing—such as periodic payments, maintenance checks, or service reporting. If such conditions exist, evaluate them as real ongoing obligations, not as optional add-ons.
In Lifetime Benefits Solutions, supplier credibility is often visible in process, not promises. Look for evidence such as:
If a supplier avoids details, keeps language vague, or offers only verbal explanations, you should treat the solution as higher risk. Good arrangements should be understandable at the time of purchase, not clarified after a problem occurs. In procurement practice, a strong indicator of future reliability is whether you can obtain answers in writing today—especially answers to edge-case questions (for example, “What if the product is discontinued?” or “What if I replace it with an upgraded model?”).
Credibility also shows up in how the supplier handles customer identity. Many programs rely on matching an identifier (serial number, registration ID, or customer account) to coverage records. A mature supplier ensures that those identifiers are captured at enrollment and are retrievable later. If enrollment is cumbersome or requires specific forms that are easy to miscomplete, that can create long-term eligibility friction. The program might still be good, but it will be harder to claim later without administrative hassle.
When evaluating supplier credibility, pay attention to how they define responsibilities. For instance, who schedules service? Who ships parts? Who pays shipping? Who is responsible for diagnosis? Who decides whether a repair is warranted? In strong programs, responsibilities are clearly assigned to avoid “handoff gaps” that can delay resolution. If the supplier’s documentation repeatedly delegates decisions without guidance, customers end up caught in the middle between partners, departments, or process steps.
The practical availability of good benefits often depends on local service capacity. When a plan references coverage “nearby,” it typically means you may receive support from a network of providers within a certain travel radius or service region. For customers, this matters because:
As a rule, align your purchase decision with your actual usage pattern—how frequently you anticipate needing service and whether you plan to stay in the same service region over time.
“Nearby” can sound simple, but in many real programs it includes subtle conditions. For instance, the “service region” may not include installation if the product is used in a location that requires a special compliance category, even if a partner exists. Or the definition of “nearby” may apply only to first-contact diagnosis, with actual repair performed elsewhere. Another common scenario: “nearby” includes only certain coverage types (like troubleshooting) but not parts replacement requiring onsite service. If you plan to use the service in a way that requires physical work, confirm that the full service scope is available within your region, not just helpdesk support.
Also consider how the supplier deals with distance beyond the “nearby” region. Do they offer shipping replacement parts? Do they authorize remote diagnostics? Are there conditions that allow you to receive service out of region? The best programs explain these alternatives. The riskier programs merely state that service is “available nearby” without clarifying what happens if you cannot access a local provider.
Finally, think about future mobility. If you move, will you have to re-register? Will the coverage transfer seamlessly, or will the supplier treat the new location as a different service region? “Lifetime” that does not accommodate relocation is still valuable to some customers, but it should not surprise you later. Relocation should be handled explicitly in the contract or in an addendum. If it isn’t, ask for it in writing.
Lifetime Benefits Solutions are ultimately risk-reduction instruments. A professional buyer treats them as a contract with enforceable terms. To reduce uncertainty, focus on:
This is consistent with top practices in contract lifecycle management: clarify assumptions early, keep documentation, and ensure compliance with stated requirements.
Risk management also includes anticipating denial triggers. Many lifetime programs include exclusions that are common across industries, such as damage from misuse, unauthorized modifications, or use outside intended parameters. Those exclusions aren’t necessarily bad; they define boundaries. The real issue is whether the program also outlines a clear method to resolve borderline cases. For example, if you have accidental damage that might be categorized as “misuse,” does the supplier allow an evaluation process? Does it explain how decisions are documented? A credible supplier provides a path for dispute or reconsideration.
In addition, consider the “parts reality.” Over time, parts become obsolete. For lifetime benefits, suppliers must decide whether they will source discontinued parts, use refurbished equivalents, or offer replacement with an updated model. Each approach can be fair if explained. It becomes risky when you’re told later that replacement will be “equal” or “comparable” without specifying what that means, what performance equivalency standards exist, or how costs like shipping and labor are handled in alternative solutions.
Another risk dimension is operational capacity. Even the best supplier can experience high demand, supply chain issues, or staffing shortages. Mature programs address this by describing expected service timelines, triage rules, and how they communicate delays. When the program contains a timeline but no mechanism for delays, customers can feel trapped by conflicting expectations. Ask what happens when response times cannot be met. A good answer might include alternative resolution options, temporary fixes, loaner units, or proactive communication windows.
This section converts practical “additional important information” into a clear, structured supplement. It is designed to help you compare solutions consistently.
| Evaluation area | What to look for in Lifetime Benefits Solutions | Why it matters over time |
|---|---|---|
| Coverage definition | Explicit list of covered services, parts, labor, and upgrade pathways | Prevents disputes when claims occur years later |
| Meaning of “lifetime” | Ownership period, product lifecycle, or membership term—stated in writing | Ensures you understand the commitment boundary |
| Eligibility & proof | Registration requirements, document retention, and identifier rules | Determines whether benefits remain accessible |
| Service availability (“nearby”) | Service radius, partner network locations, and scheduling rules | Impacts response time and feasibility of repairs |
| Exclusions and conditions | Maintenance requirements, usage limitations, and prohibited modifications | Reduces the chance of denial due to preventable issues |
| Claims workflow | How to submit requests, expected response times, escalation steps | Improves experience and accountability |
| Transferability | Whether benefits carry to new owners and how that is verified | Protects value if you change ownership |
| Pricing structure | Upfront premium, bundled subscription terms, annual fees, and caps | Helps you compare total cost of ownership |
| Substitution rules | How replacements work if the original parts are discontinued | Prevents “equal to what?” disputes |
| Communication standards | How delays are communicated; what updates you receive | Reduces uncertainty during long repairs |
Because the phrase “lifetime benefits” is contract-based, there is less value in citing industry-wide performance numbers that vary by sector and region. Instead, buyers should rely on widely used governance principles for warranties and service agreements, and on consumer-protection concepts that emphasize clear terms and fair disclosures. For background, consult:
Beyond these references, it’s often helpful to recognize that service programs are operational systems. Therefore, “good program design” usually includes: transparent enrollment (so eligibility is correct), clear coverage boundaries (so claims are predictable), enforceable response workflows (so customers are not stuck), and fair escalation or complaint handling (so disputes can be resolved). When a supplier designs for operational realities, its lifetime offering becomes more trustworthy than a simple marketing claim.
Another helpful lens is to look at how documentation is structured. Some suppliers provide a single certificate and rely on it as the authority. Others provide terms pages but do not include operational instructions. Still others include both but hide the key parts in dense language. The best suppliers provide accessible documentation, often in layered format: a summary of coverage, the full terms for review, and the practical claim steps for immediate use. That layered structure reduces errors during onboarding and reduces confusion during a claim.
Use this method to evaluate any provider systematically—especially if the offer includes good coverage and “nearby” service constraints.
To expand the same method into more “edge-case capable” evaluation, add two optional steps when you want to reduce future surprises:
These steps may feel extra, but they’re exactly where many “lifetime” programs become complicated. By confirming substitution rules and life-change handling up front, you’re essentially auditing the supplier’s operational readiness.
Lifetime Benefits Solutions often include conditions intended to keep service quality predictable. While the exact terms vary, these requirements commonly appear:
Review these points before purchasing so that your later experience is aligned with the provider’s operational and contractual framework.
It’s also useful to interpret these conditions in terms of “compliance friction.” Every requirement creates an opportunity for mistakes: missed maintenance intervals, expired registration deadlines, or lost documentation. You’re not only trying to decide if the program is fair; you’re also deciding if it’s realistic for you to comply over time. Some customers can easily keep routine service records. Others may not. If eligibility depends heavily on strict timing and documentation, then the value of lifetime benefits depends partly on your ability to maintain proof.
Where possible, choose programs that provide helpful compliance tools, such as:
Even a small improvement in compliance tooling can significantly reduce the chance that you accidentally lose eligibility. Because lifetime programs extend far into the future, the risk is not only the technical risk of failure but also the administrative risk of noncompliance.
From a professional perspective, very customer dissatisfaction in good programs is not caused by the existence of exclusions; it is caused by mismatches between expectations and written terms. Strong providers tend to:
Conversely, weaker programs often fail in four recurring areas:
To go deeper, consider “micro-failures,” not just big failures. A lifetime program can be generally good, yet still disappoint due to smaller operational issues, such as:
These micro-failures matter because lifetime benefits are meant to improve long-term reliability. Even if coverage is theoretically broad, operational friction can make the coverage feel unavailable. This is why operational maturity—document clarity, escalation procedures, and consistent partner governance—often predicts customer satisfaction more than the coverage headline itself.
One additional place where success and failure diverge is how suppliers treat customer feedback. Mature suppliers often have a structured complaint handling pathway. They log, analyze, and use complaints to refine procedures. ISO 10002 is one example of a formal approach to complaint handling that emphasizes fairness, transparency, and resolution. While no single standard guarantees excellent service, programs that align with complaint-handling principles typically deliver better outcomes when problems occur.
Even well-intentioned providers can include constraints that customers don’t anticipate. These constraints may not be “hidden” in a deceptive sense, but they may be easy to miss in dense terms. Common hidden constraints include:
To avoid missing these constraints, request a clear coverage summary in plain language plus the full terms. If a supplier refuses to provide a coverage summary or only provides a marketing brochure, treat that as a risk signal. A good supplier will help you understand the practical boundary of the benefits, not just the general concept.
Another technique is to ask for a “claim scenario checklist.” For example, you can ask, “What documents would I need if my product needs a replacement due to discontinued parts?” or “What would happen if the serial number changed after a refurbishment?” The supplier’s ability to answer with clear instructions is a strong sign that the program is operationally mature.
Sometimes the difference between a good lifetime program and an “okay in theory” program comes down to a handful of questions. Use these as a targeted list. Good suppliers will answer directly and consistently.
Coverage clarity
Definition of lifetime
Eligibility and proof
Claims process and timelines
Local service and logistics
Transferability and life changes
The goal is to force the supplier to articulate operational details, not just conceptual benefits. If you can’t get these answers clearly, you’re at higher risk of a gap between promise and experience.
Lifetime Benefits Solutions appear in multiple contexts. The evaluation criteria remain similar, but the “what matters most upfront” priorities can change by category. Below are examples of how to tailor your comparison.
1) Consumer products with lifetime service programs
If the program is tied to a product (e.g., appliances, electronics, tools), confirm:
2) Business equipment and fleet-style service agreements
If the program supports equipment used by a business, you may need additional clarity on:
3) Membership-based support programs
If “lifetime” is tied to membership, evaluate:
4) Subscription support or software-like lifetime coverage
Some lifetime benefits are for “support” rather than physical repair. In these cases, confirm:
In each category, the structure remains contract-based. But the “operational boundary” changes. Physical goods require logistics and part substitution. Membership and support programs require system access rules and version lifecycle policies. The best evaluation approach is always to map your real usage and then check whether the program’s operational rules align with it.
Claims workflow is one of the most underappreciated differences between suppliers. Two providers can offer similar coverage lists yet deliver dramatically different user experiences due to workflow complexity. A good claims workflow typically includes:
If you can, ask to see an example of a completed claim ticket (with sensitive data removed). Many suppliers will not share full internal records, but they may share a redacted sample or a description of what you can expect at each stage. That can tell you whether the workflow is mature or whether customers must repeatedly re-explain their case.
Workflow maturity also includes “failure tolerance.” For example, what happens if the customer forgets a document or can’t provide an identifier quickly? Mature programs often allow temporary validation and then request missing documents after the claim begins. Less mature programs may require full documentation before any meaningful progress happens, which can delay solutions.
Transferability is one of the biggest “future value” factors for many customers. Even if you plan to keep the product indefinitely, life changes happen: you might sell it, give it as a gift, or relocate. Therefore, your evaluation should treat transferability as a practical risk reducer.
When assessing transferability, confirm:
Also ask about “proof of transfer.” If the supplier requires receipts or specific forms, ensure that the original owner still has them. Some suppliers provide a “transfer code” or have an online process to reduce proof dependence. These features increase the likelihood that transfer will be smooth.
Relocation is similar but different. Even if the product stays with you, service availability may change because “nearby” is geographic. Confirm whether relocation triggers revalidation and whether it affects the speed of service or availability of certain claim types.
“Lifetime benefits” often hinge on substitution policies, because over time the original parts or exact products may not be available. Replacement rules can determine whether the program feels truly valuable when claims occur late in the lifecycle.
When evaluating substitution rules, seek clarity on:
A strong substitution policy makes the program usable. A weak one forces customers to accept an ambiguous outcome. If you can obtain written examples (“in similar cases, we replaced with X or Y”), that’s even better. The supplier that has already planned substitution outcomes is usually the one that will treat your claim fairly under the constraints of real-world inventory.
Even with perfect coverage, repairs and service can take time—especially when parts must be sourced or when partners schedule work around availability. What distinguishes a good lifetime benefits program is how it manages communication when delays occur.
Look for a supplier that provides:
In many customer experiences, delays become intolerable when they are combined with uncertainty. If a program promises “lifetime” service but the operational experience includes unpredictable delays without updates, customers may feel the promise is empty. Conversely, a program that communicates well—even if resolution takes longer—often feels more reliable because customers are not left guessing.
Many lifetime programs require routine maintenance or condition requirements to stay eligible. This requirement can be reasonable: it ensures safety, prevents preventable failures, and reduces disputes about causality. However, customers should aim to choose programs where these conditions are feasible and clearly defined.
To evaluate maintenance requirements, ask:
If maintenance compliance is strict and documentation is hard to obtain, the program might still be valuable, but you should plan how you will store and prove compliance. A lifetime program that cannot practically be complied with is an administrative burden that undermines its purpose.
Also watch out for maintenance requirements that are vague or overly broad. For example, “maintain according to manufacturer instructions” can be fine if instructions are clear and accessible. But if the supplier uses broad phrasing without clear schedules or acceptance criteria, customers may face uncertainty later. The best providers clarify exactly which maintenance tasks are required and the level of documentation needed.
Even the best lifetime program can be difficult to claim without documentation. The difference between a smooth resolution and a denial or delay often comes down to whether the customer can prove eligibility and compliance. Create a documentation system early.
Common documents to keep include:
For practicality, store these in both local and cloud form where possible. If the supplier provides a portal, keep screenshots or export confirmations in case you lose access later. Lifetime programs extend beyond normal memory and document retrieval timeframes. A simple habit early can prevent a painful experience later.
Lifetime Benefits Solutions are good, contract-based programs that provide defined benefits over an extended period. “Lifetime” should be interpreted according to the written terms—commonly tied to product ownership, membership duration, or a specific service lifecycle.
Not necessarily. Many programs include limits such as frequency caps, eligibility conditions, or exclusions. The critical step is to confirm which services are included, how claims are handled, and what exceptions apply.
Compare written scope, eligibility requirements, claims workflow, and “nearby” service constraints. Look for transparent terms, documented escalation paths, and evidence of consistent support operations.
Often, yes. Lifetime programs may require routine maintenance, inspections, or authorized service to remain eligible. Always verify the specific conditions in the agreement and keep relevant proof.
In practice, “nearby” usually indicates service within a defined geographic radius or through a local network. Your turnaround time may vary based on local partner availability and logistics.
Some programs allow transfer, others do not, and many require verification steps. Check the transferability clause and document how eligibility changes with ownership.
Convert pricing into a value framework: total cost, covered services, caps or frequency limits, and the term definition of “lifetime.” Then assess risk reduction by reviewing exclusions and the claims process.
Use the escalation path stated in the contract. Gather documentation, verify whether you met any conditions (maintenance, usage, registration), and request clarification in writing. If the provider has a formal complaints process aligned with customer-governance standards, follow it.
While “lifetime benefits” varies by industry, governance principles and consumer-protection expectations emphasize clear disclosures and fair processes. Standards such as ISO 10002 (complaint handling) can be relevant to how service programs resolve issues.
Keep proof of purchase, registration confirmations, serial numbers or identifiers, maintenance records, and copies of all correspondence. If service is performed by partners, retain work orders and invoices.
“Equivalent replacement” typically means a substitute part or product that matches functional requirements or performance standards. The most reliable programs define equivalency in writing (e.g., same capacity, similar specifications, comparable performance). If the terms are vague, ask for specific criteria and examples of substitutions made in similar cases.
Often yes, but it depends on the substitution policy. Some programs cover discontinued items by using refurbished parts, updated models, or reimbursement under defined rules. Confirm whether discontinued parts are substituted, how performance equivalency is handled, and whether any costs (shipping, labor, difference-in-price) apply.
If you’re outside the service region, the program may still provide remote troubleshooting or allow shipping for parts or repairs. The key is to confirm whether remote alternatives exist and how resolution timelines change. Ask the supplier to explain the practical logistics when you are outside “nearby.”
Timelines vary by claim type, service region, and parts availability. A strong provider publishes or states expected response times and resolution windows. If delays occur, good programs explain how and when you’ll be notified and what alternative options may be offered.
Typically, coverage should remain within the contract terms you accepted. However, some programs are structured around the supplier’s service lifecycle and may allow modifications in certain circumstances (e.g., discontinuation of a product line). The best approach is to locate the exact contractual language about policy changes, product discontinuation, and how those events affect your specific coverage.
Lifetime Benefits Solutions can be a strong value proposition when the benefits are clearly defined, eligibility is straightforward, and the supplier’s operational model supports real-world service—especially when “nearby” logistics affect turnaround times. The top outcomes come from comparing scope in writing, confirming requirements early, and aligning price with the actual coverage boundaries you’re likely to use.
If you want to evaluate with maximum confidence, treat the contract like an operational blueprint. Read the definitions of “lifetime,” map the claims workflow, test substitution and life-change scenarios, and verify locality rules. When you do that, lifetime benefits become measurable and usable rather than an abstract promise.
If you want, tell me your industry context (e.g., consumer product warranty program, equipment service plan, subscription support, or another category) and the typical “lifetime” definition you’re seeing. I can help you build a tailored comparison checklist for the specific supplier types and terms you’re evaluating.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services

Pet Insurance Essentials: Coverage, Costs, and Resources Explained
In recent years, pet ownership has seen a significant surge. Pets, whether they're dogs, cats, birds, or other animals, have increasingly become integral parts of our families. With this growing bond, there is a rising awareness of the importance of pet health and well-being. Just as health insurance is crucial for humans, pet insurance is becoming an essential consideration for pet owners. This article aims to provide a comprehensive understanding of pet insurance, covering its importance, types of coverage, associated costs, and valuable resources to help you make an informed decision.
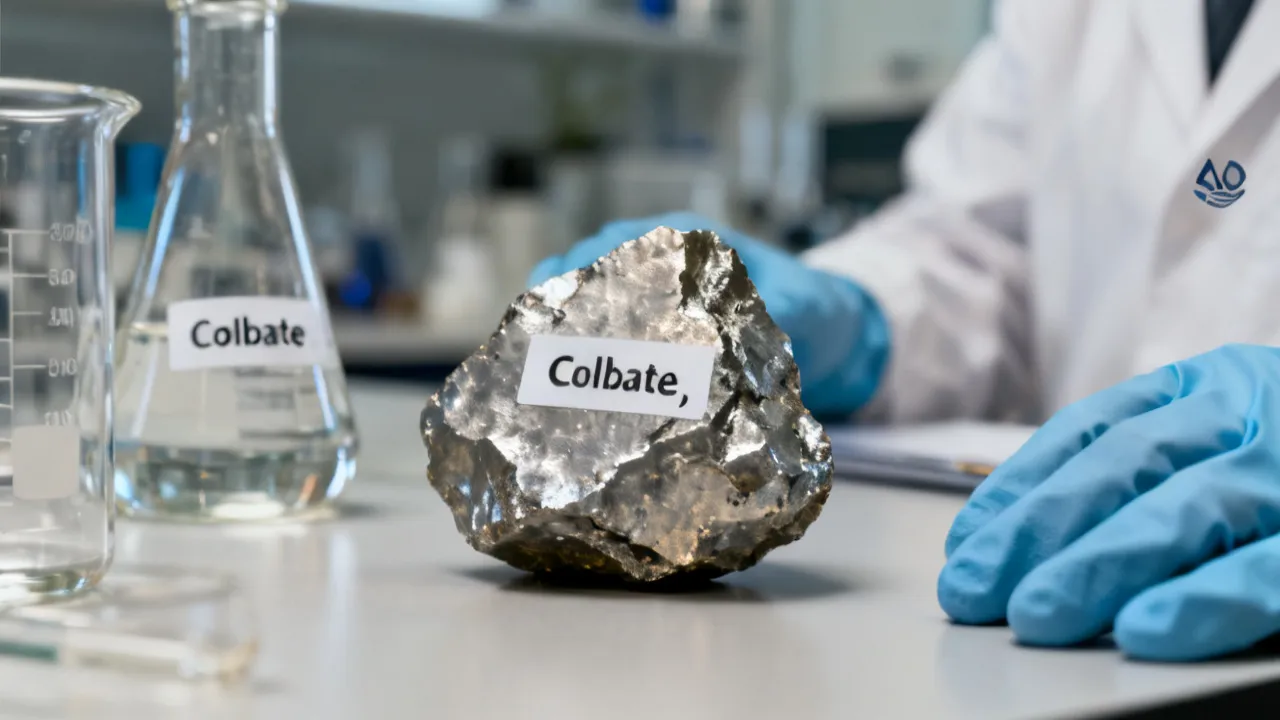
Colbate Explained: Uses, Sourcing, and Top Practices
This guide explains Colbate from a practical industry viewpoint, covering what it is, how suppliers typically handle it, and what buyers should verify before purchase. It also summarizes objective background on related terminology, common application considerations, and due-diligence steps. Readers will find a comparison table, requirements, and targeted FAQs to support confident sourcing decisions.

Strategies for Financial Security and Legacy Planning
Life insurance isn't just about what happens after you pass—it's a strategic tool in a comprehensive plan for your financial security and estate planning.

Navigating Insurance Costs for Seniors: Essential Tips and Advice
As we age, healthcare costs and the complexity of managing them can become increasingly burdensome. For many seniors, navigating insurance costs is a crucial aspect of ensuring financial stability and maintaining health. This guide aims to provide you with essential tips and advice on how to manage and potentially reduce these costs effectively.
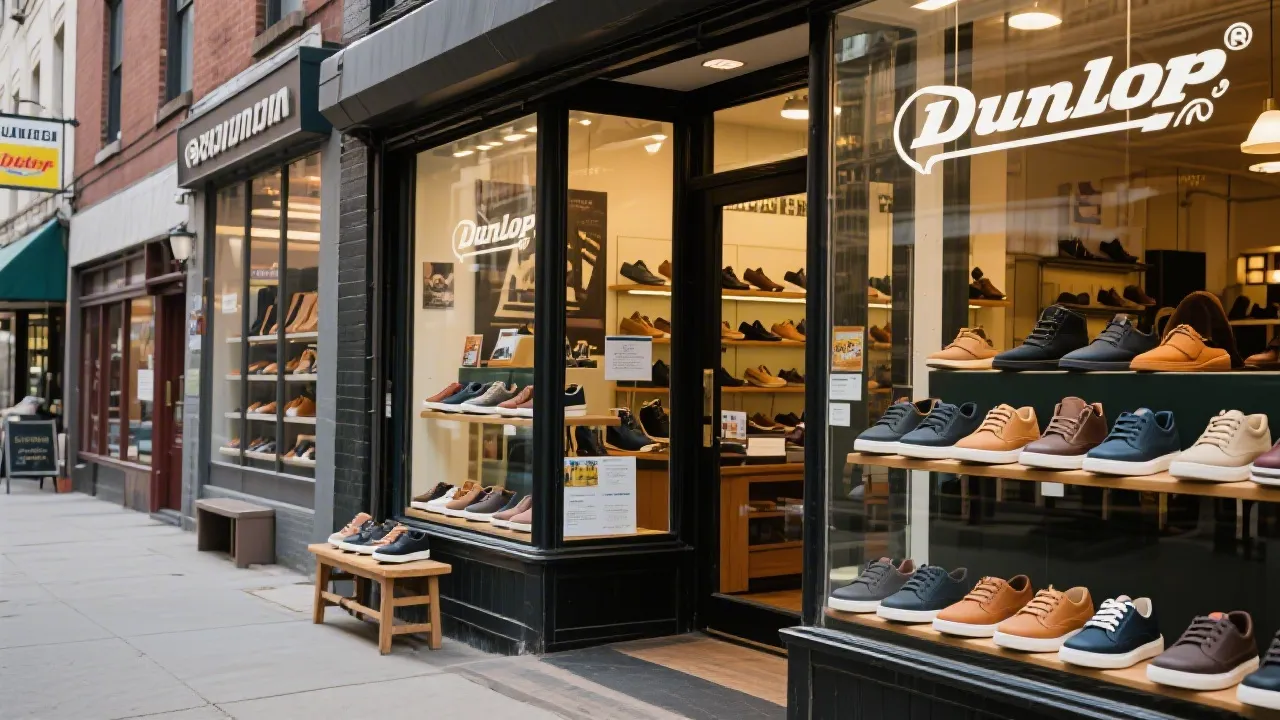
Discovering Dunlop Brooklin Footwear
This article delves into Dunlop Brooklin, a prominent name in the footwear industry known for its exceptional quality and innovation. Dunlop is recognized for its wide-ranging collection of shoes designed to meet diverse customer needs, from casual wear to professional attire. This guide provides an in-depth analysis of Dunlop Brooklin and its offerings, revealing why it stands out in the market.
Your Guide to Understanding Car Insurance Coverage
Navigating car insurance can be puzzling. Fortunately, this guide illuminates coverage types and choosing the right provider.